Changing Your Company Secretary in Singapore: A Guide to a Smooth Transition

Changing Your Company Secretary in Singapore: A Guide to a Smooth Transition

The company secretary plays a central role in maintaining statutory registers, managing corporate records, and tracking filing deadlines. When a company changes its secretary or corporate secretarial provider, a poorly managed handover can create a gap in responsibility, particularly between the outgoing secretary’s departure and the incoming secretary’s first review.

The risk is self-evident. If both parties assume the other is handling a particular filing, a filing deadline can be missed even when the company has otherwise maintained a clean compliance record.

This article explains when companies typically switch secretaries, what to prepare, how the handover works, and which controls can help prevent missed filings.

When Companies Decide to Switch

Companies typically change their company secretary for one of three reasons. Understanding the reason for the switch helps the incoming company secretary identify the most immediate priorities and address any outstanding matters effectively:

  • Service issues: Late filings, unexplained penalties, or slow responses to routine queries may indicate that a change in company secretary is necessary. In some cases, these issues persist for an extended period before a missed deadline ultimately prompts the switch.
  • Growth and complexity: Changes such as the admission of new shareholders, group restructuring, regional expansion, or plans for a public listing may require a higher level of corporate secretarial support than a provider serving a simpler corporate structure can offer.
  • Cost and continuity: Companies may choose to consolidate their secretarial function with other corporate service providers to achieve greater efficiency. A change may also be required where an individual company secretary resigns, retires, or is otherwise unable to continue in the role.


Whatever the trigger, the switch itself need not give rise to compliance risks. A well-planned handover can address potential gaps before they develop into compliance issues.

What to Prepare Before the Handover

A smooth transition starts with ensuring that the necessary records and information are available and up to date. Preparing these materials before the handover provides the incoming secretary a clear understanding of the company’s current compliance position, governing practices, and upcoming obligations.

  • Register inventory: Statutory registers, including the register of members, directors, charges, and registrable controllers should be complete, accurate, and readily available for review.
  • Filing calendar: Key filing deadlines, including the next annual return and any other pending lodgements with the Accounting and Corporate Regulatory Authority (ACRA) should be identified and documented. This should include matters and filings already in progress with the outgoing secretary.
  • Corporate records: The company’s business profile, constitutional documents, minutes and resolutions, statutory records, and relevant appointment and resignation documents including consent to act as director or company secretary should be organised and made available to the incoming secretary.


This preparation enables both parties to establish a clear understanding of what has been completed, what remains outstanding, and where responsibility sits on the handover date. Clear accountability at the point of transition helps reduce the risk of missed filings, overlooked obligations, and unnecessary compliance issues.

The Handover Steps and Statutory Filings

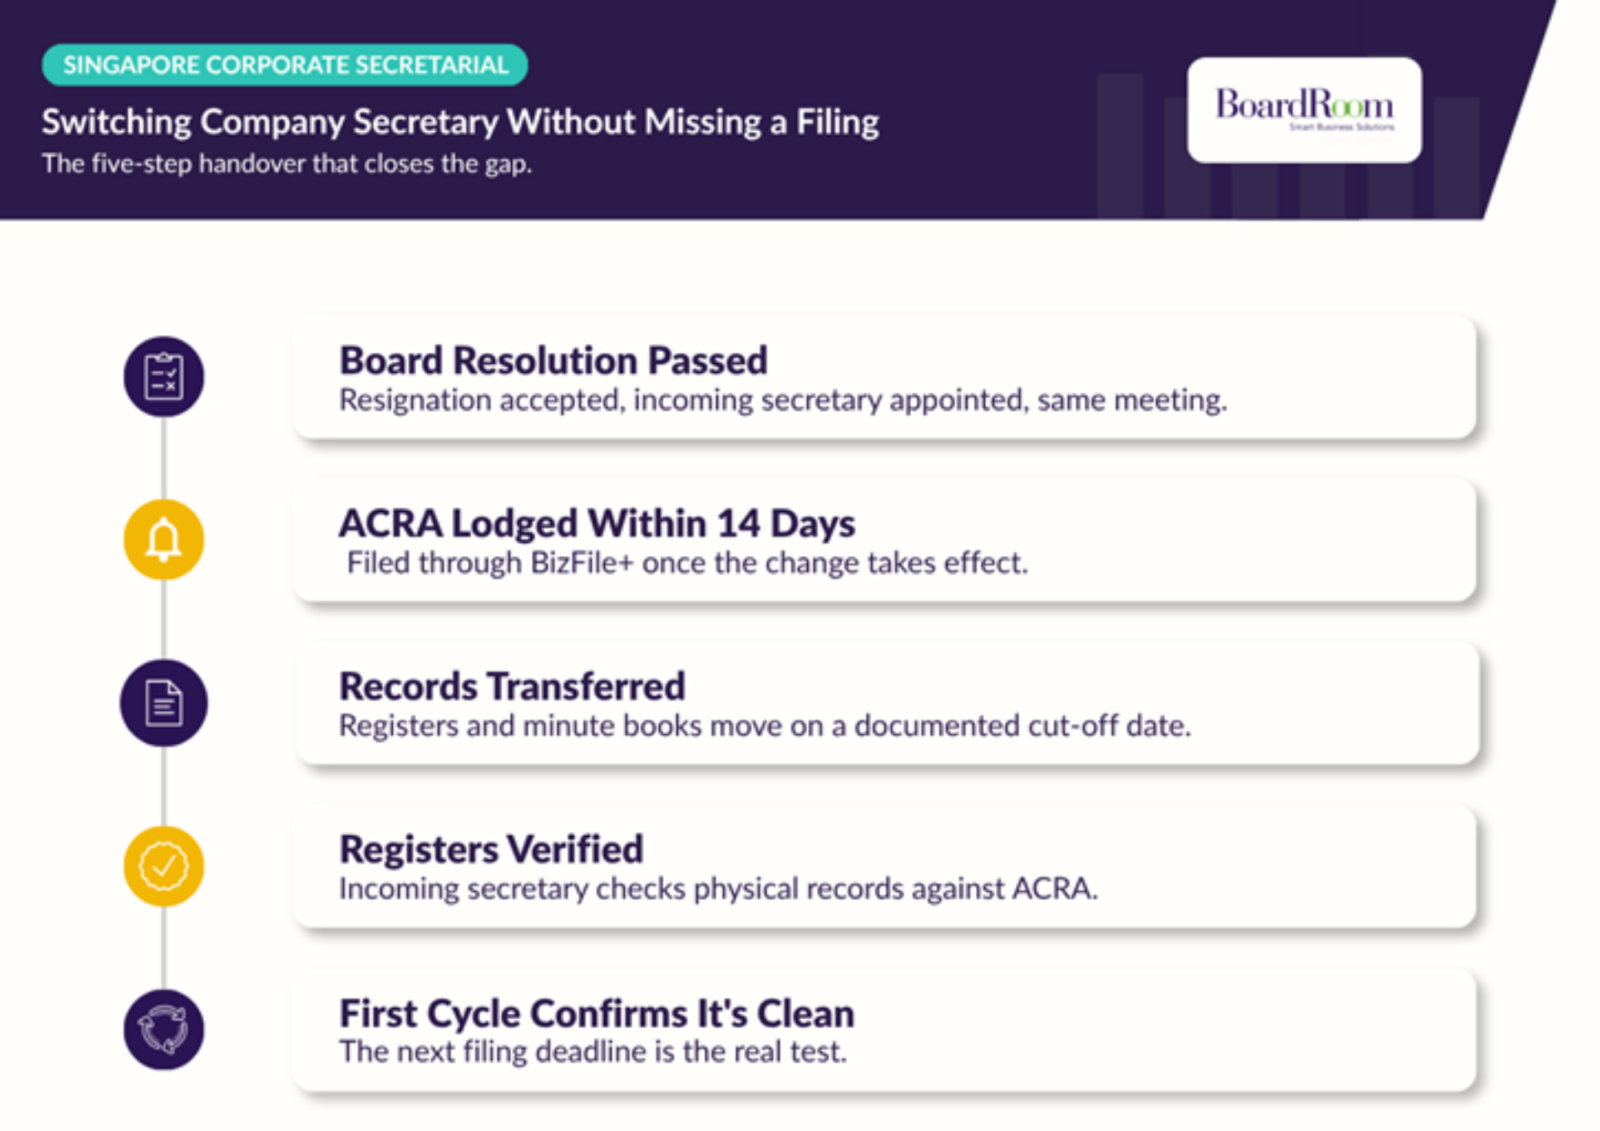
A company secretary transition involves both the formal change of appointment and the transfer of records, information and ongoing responsibilities. Careful coordination of these steps helps ensure continuity and minimise the risks of missed deadlines and compliance gaps:

  • Board resolution: The board should accept the outgoing secretary’s resignation and approve the appointment of the incoming secretary, ideally at the same board meeting to ensure a seamless transition.
  • ACRA lodgement: Changes relating to company officers, including the appointment or cessation of a company secretary, must be lodged with ACRA via BizFile+ within 14 days of the effective date of the change.
  • Records transfer: Statutory registers, minute books, corporate records, and other records are transferred based on the agreed cut-off date. The scope of the handover and the date on which responsibility passes to the incoming company secretary should be clearly documented.
  • Verification and reconciliation: The incoming secretary should review the company’s records against the information maintained by ACRA and identify any discrepancies, incomplete filings, or outstanding compliance matters requiring the follow.


A clearly documented handover process provides certainty on the allocation of responsibilities during the transition period. This helps ensure that ongoing filings, statutory deadlines, and governance obligations continue to be monitored and addressed without interruption.
Risks and Controls During the Transition

The period during a company secretary transition is often where accountability can become less clear. Three simple controls can help protect the company during this time:

  • Clear ownership: Every filing or corporate action due during the transition period should have a named person responsible for completing it. This should be confirmed before the outgoing company secretary ends its engagement.
  • Deadline verification: The incoming secretary should independently verify all upcoming filing deadlines and statutory obligations rather than relying solely on the information including outgoing company secretary’s calendar. This serves as an important safeguard against incomplete records and overlooked deadlines.
  • Record reconciliation: Any discrepancies between the company’s statutory records and the information maintained by ACRA should be identified and resolved as part of the transition process, rather than being deferred until the next filing cycle.


The Singapore Companies Act 1967 requires every company to have at least one company secretary and provides that the office of company secretary must not remain vacant for more than six months. Accordingly, the outgoing company secretary’s cessation and the incoming company secretary’s appointment should be carefully coordinated to ensure continuity of oversight and minimise compliance risk.

A Realistic Timeline for a Smooth Transition

Most company secretary transitions follow a broadly similar pattern, although the timeline will depend on the quality, completeness, and accessibility of the company’s records.

  • Preparation: Allow approximately one to two weeks to gather records, review statutory registers, reconcile outstanding matters, and identify upcoming filing obligations. Additional time may be needed if records are incomplete, inaccurate or outdated.
  • Formal transition: Once responsibilities, records, and outstanding matters have been confirmed, the necessary board resolutions can be passed and the relevant changes lodged with ACRA.
  • Stabilisation: Following the handover, the incoming secretary assumes responsibility for the compliance calendar and oversees the first reporting and filing cycle under the new arrangement. This helps identify any gaps and address any issues that may not have been apparent during the initial review.


While the exact timeline will vary from one company to another, the underlying principle remains the same. The more complete the records are before the transition, the smoother the transition and more effective the handover is likely to be.

A well-managed transition not only facilitates compliance continuity but also gives the incoming company secretary a solid foundation from which to support the company’s ongoing governance and regulatory obligations.

How BoardRoom Manages the Transition

BoardRoom’s corporate secretarial services are structured to minimise the compliance and operational risks that can arise during a company secretary transition:

  • Structured onboarding: A review of statutory register, a documented cut-off date, and a verified filing calendar are established at the outset of the engagement, providing clarity on the company’s current position and upcoming obligations.
  • Clear deadline ownership: Every filing due during and after the handover is assigned in writing before the transition takes effect.
  • Integrated support: Corporate secretarial services are coordinated with accounting, tax, and share registry services where the company’s structure requires it.

A Clean Handover Keeps Compliance on Track

Transitioning to a new company secretary should not disrupt your compliance obligations. The key is to approach the transition as a structured handover, supported by complete records, clear accountability, and a verified filing calendar.

With the proper preparation, the incoming secretary can take over with a clear understanding of the company’s statutory records and upcoming filing obligations, reducing the risk of missed filings, incomplete filings, and unresolved discrepancies that could otherwise affect the company’s compliance position.

BoardRoom supports Singapore companies throughout the company secretarial transition process, from initial review of statutory records and handover planning to ongoing corporate secretarial and compliance management.

If you are considering a change of company secretary, BoardRoom can help assess your current arrangements, coordinate the handover process, and ensure a seamless transition with minimal disruption to your compliance obligations.

Contact BoardRoom to discuss your requirements and plan your transition.
Retrenchment in Singapore: What Employers Must Get Right on Final Pay, Notice, and Statutory Obligations

Retrenchment in Singapore: What Employers Must Get Right on Final Pay, Notice, and Statutory Obligations

Restructuring has picked up across Singapore in 2026. Retrenchments rose from 3,830 in the first quarter to 4,500 in the second quarter, according to the Ministry of Manpower’s (MOM) advance estimates, with most attributed to business reorganisation or restructuring in sectors such as Information & Communications and Manufacturing.

Business closures have also increased. The Accounting and Corporate Regulatory Authority (ACRA) recorded 42,741 business cessations in the first eight months of 2026, 8.5% more than in the same period of 2025. When a restructuring or closure involves letting employees go, managing workforce transition lands on the payroll team.

This places significant time pressure on payroll teams. Final pay, notice, and benefit calculations must be accurate even when deadlines are tight, because an error becomes harder to fix once termination letters have been issued. A routine payroll error can be corrected in the next cycle, but a retrenchment error may not be discovered until after the employee has already left.

The reputational risk is just as high. Errors in final payments affect departing employees, while remaining staff will also notice how the process is handled. The exercise reflects how the organisation treats its people under pressure, not just whether the numbers are correct.

This article covers the employer obligations that apply during retrenchment, how to calculate final pay correctly, the statutory submissions that must not be missed, and where outsourced payroll support can reduce the risk of errors.

When Retrenchment Triggers Employer Obligations

Retrenchment is the dismissal of an employee due to redundancy or business reorganisation. It is distinct from termination for misconduct or resignation, and it matters because it determines which obligations apply and whether the employee may be entitled to a retrenchment benefit.
Employers should not characterise a redundancy as another form of termination simply to avoid retrenchment obligations. The circumstances surrounding the termination may be examined if the exercise is challenged.

These key obligations include:

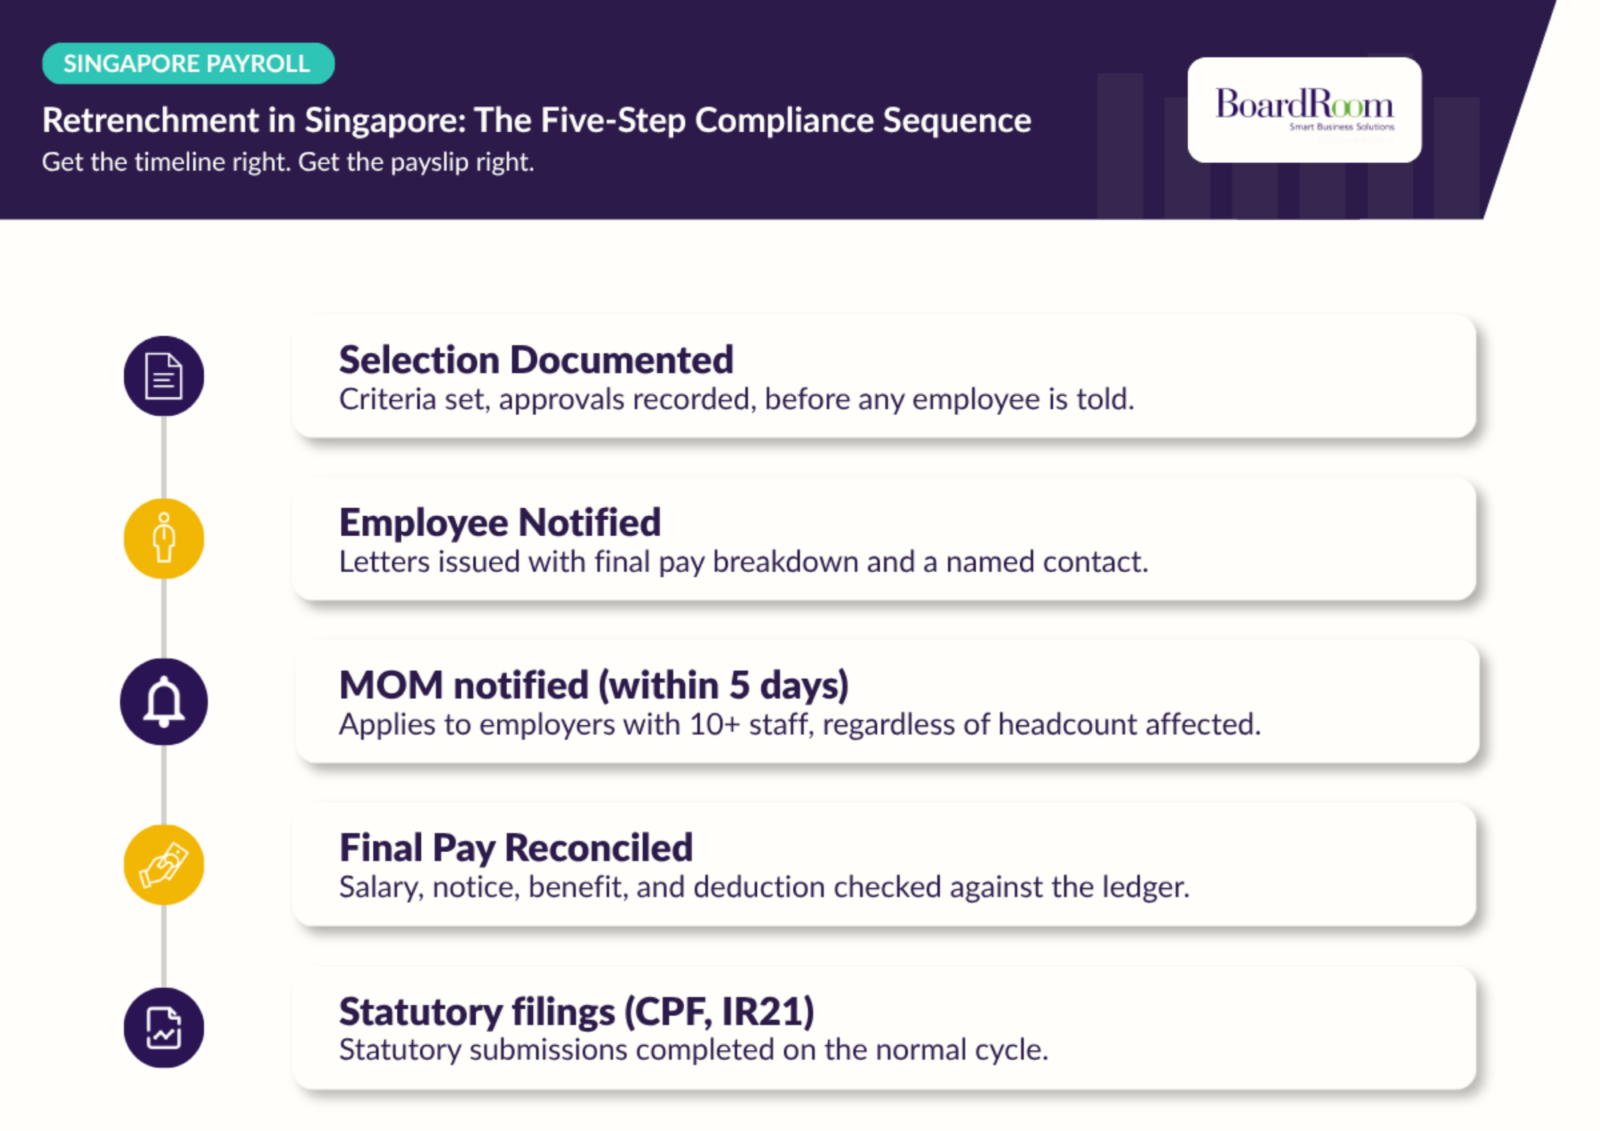
  • Notification duties: Employers with at least 10 employees must notify the Ministry of Manpower (MOM) within five working days of informing affected employees of their retrenchment. This applies even if only one employee is affected. Employers with less than 10 employees are not required to but are strongly encouraged to notify MOM of retrenchment.
  • Fair selection: Selection criteria should be objective, non-discriminatory, and based on factors such as the employee’s ability to contribute to the company’s future business needs. Employers should document the criteria before affected employees are notified, in line with the Tripartite Advisory on Managing Excess Manpower and Responsible Retrenchment.
  • Maintaining a strong local core: Employers should take a long-term view of their manpower needs and ensure that retrenchment exercises do not disproportionately affect local employees. This is among the factors considered by MOM when reviewing retrenchment notifications.

Building the Final Payment Correctly

Final pay consists of several components, each with its own calculation and compliance requirements. Getting these right before payment is easier than fixing an incorrect settlement after the employee has left.

  • Salary to the last day: This includes salary earned up to the employee’s last day of employment, unused annual leave, and any outstanding claims owed to the employee. MOM states that these salaries should be paid on the last day of work for retrenchment.
  • Notice pay: The employer must either allow the employee to serve the required notice period or provide salary in lieu of notice, based on the applicable contractual notice period specified in the employment agreement.
  • Retrenchment benefit: Employees who have served the company for at least 2 years are eligible for retrenchment benefit. Those with less than 2 years’ service could be granted an ex-gratia payment out of goodwill. The amount generally depends on the employment contract or collective agreement. MOM’s prevailing norm is between two weeks and one month’s salary for each year of service, depending on factors such as industry practice and the company’s financial position.
  • Deductions: Only lawful deductions should be made, with each deduction properly supported and clearly itemised on the final payslip.

Statutory Submissions That Must Not Slip

Retrenchment does not put the normal compliance calendar on hold. Some obligations continue as usual, while others become particularly important when an employee leaves the organisation.

Three areas require close attention:

  • Central Provident Fund (CPF): CPF contributions remain payable on salary and other components of final pay that qualify as wages. However, retrenchment or termination benefits themselves are generally not subject to CPF contributions.
  • Tax clearance for non-Singapore citizens: Where tax clearance is required, employers must file Form IR21 with the Inland Revenue Authority of Singapore (IRAS) at least one month before the employee ceases employment. Moreover, employers should withhold monies due to the employee from the point the employer becomes aware of the impending cessation. This generally applies to employees who are not Singapore Citizens, including Singapore Permanent Residents, subject to applicable exemptions.
  • Employment records: Employers must retain the required employment and salary records for the statutory period. For ex-employees, records must generally be kept for one year after the employee leaves, covering the latest two years of employment records. For tax and payroll purposes, records need to be kept for 5 years.

Payroll Documentation and Audit Trail

Accurate payroll records help employers explain final payment calculations, address employee queries, and resolve discrepancies that may arise after retrenchment. Maintaining a clear audit trail also makes it easier to trace adjustments and verify that payments were properly processed.

Employers should keep the following records for each affected employee:

  • Supporting payroll records: Salary details, leave balances, contractual entitlements, and supporting documents for applicable benefits and deductions.
  • Calculation and approval records: A breakdown of final pay calculations, including any adjustments made and the corresponding review and approval records.
  • Payslips and payment confirmations: Itemised final payslips, payroll reports, and proof of payment to verify the amounts disbursed.


These records support the broader retrenchment process, which involves several compliance requirements and deadlines, as outlined below.

Why Companies Outsource Payroll During Restructuring

Restructuring places unusual pressure on payroll teams precisely when accuracy matters most. This is often when organisations reconsider whether the exercise should be managed entirely in-house or with specialist support:

  • Capacity when pressure is highest: Internal teams may already be occupied with the wider restructuring exercise, while payroll accuracy still needs to be maintained.
  • Specialist calculations: Notice pay, leave encashment, final-pay calculations, and IR21 processing can become more difficult when deadlines are tight, particularly for teams with limited experience handling retrenchments.
  • Continuity: An external provider can keep payroll processing and compliance activities on track while the wider organisation is undergoing change, reducing the risk of missed deadlines or incomplete filings.

How BoardRoom Supports Employers Through Retrenchment

BoardRoom’s payroll services support employers through the retrenchment payroll cycle:

  • Final pay processing: Calculation and disbursement of final pay, including salary, notice pay, leave and applicable benefits, with reconciliation before release.
  • Statutory handling: Support with CPF submissions and IR21 tax clearance requirements, where applicable.
  • Controls: Maker-checker review of final settlements before release, helping reduce the risk of errors reaching departing employees.

Getting Retrenchment Right From the Start

Retrenchment is both a payroll and compliance exercise, and it is conducted under scrutiny from employees, regulators, and other stakeholders. Preparation protects both the employer and the departing employee.

Getting notice, final pay, documentation, and statutory submissions right the first time is essential. A well-controlled process reduces the risk of disputes, missed deadlines, and payment errors at a time when the organisation is already under pressure.

BoardRoom supports Singaporean organisations by managing retrenchment payroll, handling statutory filings, and providing expert tax advisory and filing services for foreign nationals needing IR21 clearance.

Contact BoardRoom to discuss how specialist payroll and compliance support can help manage your restructuring exercise.

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

Business Article

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

SHARE:
16 Oct 2026
Singapore AGM Season 2026: Insights and Trends From 167 General Meetings
167general meetings serviced in April 2026
44.53%of SGX-listed companies managed by Boardroom
+21%attendance of shareholders vs 2025
55%of physical meetings used e-polling
−26%proxy forms received, to 5,761

As the number one share registrar in Singapore and Malaysia by market capitalisation, and Singapore’s leading share registry services provider, BoardRoom serviced 167 annual general meetings (AGMs), extraordinary general meetings (EGMs), and special general meetings in April 2026. These represented 44.53% of companies listed on the Singapore Exchange (SGX).

April remains the peak of Singapore’s AGM calendar because most SGX-listed issuers close their financial year on 31 December and must hold the AGM within four months of the year end, under SGX Listing Rule 707(1) and section 175 of the Companies Act 1967.

About the data: This report covers the 167 general meetings BoardRoom serviced in April 2026. Year-on-year comparisons are based on companies that held April meetings in both 2025 and 2026.

Key takeaways

  • 64%of the 167 meetings were held in the final week of April, and 97% were held in physical mode.
  • +375%rise in hybrid attendance. Total attendance rose 21% to 19,709 among companies that met in both years.
  • 55%of physical meetings used electronic polling, and 94% of those used handsets.
  • 5,761proxy forms received, down 26%. The most common meeting now runs one to one and a half hours.

Singapore: The April 2026 Season

Meeting format: when and how companies met

Nearly two thirds of meetings were held in the final week of April. 29 April alone accounted for 21% of the total.

Meetings by week, April 2026 (n = 167)

Week beginning 13 April
13 (8%)
Week beginning 20 April
47 (28%)
Week beginning 27 April
107 (64%)

Of the meetings held on 29 April, 37% started at 10am, compared with 35% on the same date in 2025.

Physical meetings remained the norm: 97% were held in physical mode and 3% were hybrid, up from 1% in the 2025 season.

Meeting format by season

2025 season (174)1% hybrid
2026 season (167)3% hybrid
PhysicalHybrid

Communication: Hardcopy Notices Remain Universal

Every meeting mailed a hardcopy notice of meeting, proxy form, or letter to shareholders and unitholders.

Communication practice (n = 167 meetings)

Hardcopy notice, proxy form, or letter mailed
167 (100%)
Hardcopy annual report or circular available on request
138 (82%)
Hardcopy annual report or circular mailed
26 (16%)
Switched from on request in 2025 to no on-request option in 2026
3 (2%)

The 16% mailing rate is broadly in line with the 14% recorded in 2025. Making hardcopy annual reports or circulars available on request remained the most common approach, used at 82% of meetings compared with 86% in 2025.

Attendance: Up 21% Year on Year

Among the 147 companies that held April meetings in both years and reported attendance for both, total attendance rose 21% to 19,709.

Physical attendance increased by 18%, while hybrid attendance rose 375% from a low base.

Physical18,901+2,817 (+18%)
Hybrid808+638 (+375%)
Total19,709+3,455 (+21%)
Attendance, 147 companies with meetings in both years
Season Physical Hybrid Total
2025 16,084 170 16,254
2026 18,901 808 19,709
Change +2,817 (+18%) +638 (+375%) +3,455 (+21%)

Shareholder Engagement: Questions Before the Meeting

Nearly every meeting (99%) gave shareholders a way to submit questions in advance. Many companies used BoardRoom’s Question Deposition Service to receive those questions, through the channels below.

Question Deposition Service channel (Total of 83 companies)

Designated email address and post
48
Post
30
Designated email address
4
Designated email address, post and pre-registration site
1

Questions were received before 57% of meetings, up from 51% in 2025. Of these, 93% answered the questions through SGXNET ahead of the meeting. This excludes meetings that received questions only from the Securities Investors Association (Singapore).

The five topics shareholders raised most often were:

  1. Company strategy and future plans
  2. Financial performance
  3. Dividends and distributions
  4. Mergers, demergers, acquisitions and divestments
  5. Share or unit buy-backs and renewal of the share purchase mandate

Strategy questions this season were frequently framed around Middle East tensions and the resulting rise in global fuel prices, and their effect on material, freight, logistics and insurance costs, supply-chain lead times and margins. Company strategy moved to first place from second in 2025, when questions on United States tariffs drove the topic.

Voting and Proxy Processing

Electronic polling was used at 55% of physical meetings, and 94% of those used handsets rather than shareholders’ own devices.

Where paper polling was used, counting could take up to half of the meeting time.

Poll type by meeting format
Meeting format Poll type Meetings Share of format
Physical (162) Paper poll, Excel (manual) 34 21%
Paper poll, BR Poll (semi-automated) 39 24%
Electronic poll, handsets 84 52%
Electronic poll, bring your own device (BYOD) 5 3%
Hybrid (5) BYOD on site and online voting for remote attendees 3
Handsets on site and online voting for remote attendees 2

Electronic polling was used at 52% of physical meetings in 2025. This points to a continued, gradual shift towards e-polling.

Proxy deposition

A total of 118 companies used BoardRoom’s Proxy Deposition Service, the same number as in 2025. Most accepted proxies through both email and post.

Proxy Deposition Service channel (Total of 118 companies)

Email address and post
96
Post
18
Email address, post and pre-registration site
3
Email address
1
Proxy forms, 2025 vs 2026
Proxy forms 2025 2026 Change
Received 7,780 5,761 −2,019 (−26%)
Processed 6,798 4,916 −1,882 (−28%)

The five resolutions that attracted the most poll votes were unchanged from 2025:

  1. Re-election of directors
  2. Financial report
  3. Auditor
  4. Dividend
  5. Directors’ fees

Meeting Duration

Meetings ran longer than in 2025. The largest duration category was one hour to under one and a half hours, covering 36% of meetings.

Overall, 62% of physical meetings lasted between 30 minutes and one and a half hours.

Duration of all 167 meetings

Under 30 minutes
9 (5%)
30 minutes to under 1 hour
43 (26%)
1 hour to under 1.5 hours
60 (36%)
1.5 hours to under 2 hours
33 (20%)
2 hours to under 2.5 hours
20 (12%)
2.5 hours and above
2 (1%)
Duration by meeting format
Duration Physical Hybrid Total Share
Under 30 minutes 9 0 9 5%
30 minutes to under 1 hour 42 1 43 26%
1 hour to under 1.5 hours 59 1 60 36%
1.5 hours to under 2 hours 32 1 33 20%
2 hours to under 2.5 hours 19 1 20 12%
2.5 hours and above 1 1 2 1%
Total 162 5 167 100%

Among the 157 companies that held meetings in both years, meetings lasting between one and two hours rose from 43% to 57% of the total, while meetings lasting less than an hour fell from 41% to 31%.

Duration, 157 companies with meetings in both years
Duration 2025 season 2026 season Change
Under 30 minutes 11 8 −3
30 minutes to under 1 hour 54 40 −14
1 hour to under 1.5 hours 37 58 +21
1.5 hours to under 2 hours 30 31 +1
2 hours to under 2.5 hours 21 18 −3
2.5 hours and above 4 2 −2

Refreshments and Door Gifts

Refreshments remained the most common provision. In 2026, 57% of meetings provided refreshments only, while 34% provided neither.

Among the 156 companies with meetings in both years, the 2025 figures were 68% for refreshments only, 2% for vouchers or door gifts only, and 30% for neither.

Provision at 167 meetings

Refreshments only (95)Voucher or door gift only (15)Nothing provided (57)

Among the 156 companies with April meetings in both years, fewer provided refreshments only, while vouchers and door gifts increased from a low base.

Overall, 6% fewer provided refreshments, vouchers or door gifts than in 2025.

Provision, 156 companies with meetings in both years
Provision 2025 2026 Change 2025 to 2026
Refreshments only 106 89 −16%
Voucher or door gift only 3 13 +333%
Nothing provided 47 54 +15%

Key Considerations for the Next Season

  • Book early for the final week of April64% of meetings were held during that week, with 21% on 29 April alone.
  • Plan for more attendees and longer meetingsAttendance rose 21%, while the typical meeting runs one to one and a half hours.
  • Treat hybrid as a live optionOnly 3% of meetings offered the option, but hybrid attendance rose 375%.
  • Consider electronic pollingPaper polls took up to half of the meeting time, while electronic polling was already used at 55% of physical meetings.
  • Use the pre-meeting question window57% of meetings received questions in advance, giving companies an opportunity to address shareholder concerns before the live session.

BoardRoom’s share registry, AGM management, e-polling and proxy processing teams supported BoardRoom manages 44.53% of SGX-listed companies through the 2026 season, and the same teams carry issuers through dividend distribution after the meeting, the basis on which BoardRoom remains Singapore’s leading share registry services provider.

BoardRoom’s Malaysia AGM season report covers January to June 2026.

About BoardRoom

One BoardRoom. One Partner. Complete Corporate Services Delivered Seamlessly.

From start-up to scale, BoardRoom supports growth with integrated compliance expertise, bringing corporate secretarial, tax, payroll, accounting, fund solutions, share registry, employee share plans and sustainability services together through a single trusted partner.

To discuss support for your next general meeting in Singapore, contact BoardRoom.

Frequently Asked Questions

1. When must an SGX-listed company hold its AGM?

Within four months of its financial year end, under SGX Listing Rule 707(1) and section 175 of the Companies Act 1967.

2. How does e-polling work at a Singapore AGM?

Shareholders and proxies register on arrival and receive a handset, or use their own device, to cast votes on each resolution. Votes are tallied electronically and the scrutineer certifies the result, which removes manual counting.

What XBRL Filing Means for Singapore Companies and When Outsourcing Makes Sense

What XBRL Filing Means for Singapore Companies and When Outsourcing Makes Sense

For companies, eXtensible Business Reporting Language (XBRL) filing means converting financial statements from a document designed for people into structured financial data that the Accounting and Corporate Regulatory Authority’s (ACRA) systems can read, validate and compare. XBRL uses digital tags to identify financial information, such as revenue, assets, and net profit, so that the data can be processed consistently by software.

This is more than a file-format conversion. The company must determine which filing requirement and XBRL template apply, map each relevant financial-statement item to the ACRA Taxonomy, complete the required fields, resolve validation issues, and ensure that the XBRL data agrees with the financial statements presented at the annual general meeting or circulated to members.

The practical question is therefore not only whether the company can use the free BizFinx Preparation Tool, but whether the finance team has the capacity, accounting judgement, and current taxonomy knowledge to prepare an accurate filing within the annual-return timetable. This article explains what XBRL filing involves, the common challenges, and why outsourcing makes sense.

What XBRL Filing Means for Companies

ACRA states that Singapore-incorporated companies must prepare financial statements, except for dormant relevant companies, and must file financial statements with ACRA unless exempted. The filing format and extent depend on the company’s nature and size. Companies should therefore first confirm whether filing is required and which XBRL template applies.

The main filing categories are:

Full XBRL 
  • Applies to companies that are not classified as small and non-publicly accountable. 
  • The template contains about 210 data elements. 
Simplified XBRL 
  • Applies to smaller and non-publicly accountable companies, where both revenue and total assets do not exceed S$500,000 for the current financial year. 
  • The template contains about 120 data elements. 
XBRL FSH 
  • Applies to banks, finance, and insurance companies regulated by the Monetary Authority of Singapore (MAS). 
  • The template contains about 80 data elements. 

Companies such as dormant relevant companies and solvent exempt private companies may be exempt from filing financial statements, while companies limited by guarantee, foreign companies, and companies using other accounting standards approved by ACRA have separate filing requirements.

Companies generally map and validate the financial statements in the BiZFinx Preparation Tool, upload the XBRL file, and then file the annual return in BizFile+. ACRA notes that if the annual return is not lodged after the XBRL upload, the uploaded date may lapse and require re-uploading.

Why XBRL Filing Can Be Challenging

The most demanding part is often mapping. ACRA describes its taxonomy as a dictionary for XBRL language. Preparers must match line items in the financial statements to the relevant taxonomy concepts, using one-to-one, many-to-one, one-to-many, or best-fit mapping where appropriate. This requires accounting judgement because the wording in the financial statements may not exactly match the taxonomy.

These errors can lead to amendments. If an amendment is missed and the filing remains incorrect after the deadline, penalties may follow. An accountant who has prepared hundreds of filings is more likely to recognise how unusual line items should be tagged, while a preparer completing one filing a year may be learning the process under deadline pressure.

Other challenges include keeping the XBRL file aligned with late changes to the final financial statements, checking comparative figures imported from an earlier filing, completing every applicable template, and resolving validation errors. ACRA notes that not all data elements may be imported when taxonomy versions change, so preparers must check the accuracy and completeness of comparative figures rather than rely on a simple roll-forward.

The Business Impact of Getting It Wrong

  • Penalties: An annual return filed up to three months late carries a S$300 penalty, and S$600 beyond that, applied automatically in BizFile+. Repeated breaches can bring composition sums of at least S$500, court fines of up to S$10,000 per charge, and disqualification for a director with three filing offences in five years.
  • Record: Late or corrected filings stay on the company’s ACRA record. Banks and buyers check that record before they lend or invest, and a history of late filings costs the company their confidence.
  • Internal cost: Every amendment sends the accountant back to re-map, re-validate and re-upload the file while the deadline keeps running. At year-end, that means overtime or a hire to cover the gap and drive up the cost.

Directors are responsible under Section 201 of the Companies Act 1967 for laying financial statements before the company at its AGM, and those financial statements must comply with the Accounting Standards and give a true and fair view of the company’s financial position and performance.

Why Outsourcing Can Make Sense

Factor  In-house works when  Outsource when 
Disclosure complexity  Single entity with simple accounts, same disclosures as last year.  Complex or group accounts, restructuring, a new accounting policy, or a first-time filing. 
Team capacity  Team is available during the filing window.   No internal capacity is available due to existing finance and audit commitments.  
Mapping skill  An accountant on the team has prior mapping experience in the Preparation Tool.   No team member has mapping experience, or the individual with experience has left the team. 
Cost Considerations   Internal capacity is available at no incremental cost.   Internal delivery would require overtime, reassignment of existing tasks, or additional headcount.  

Outsourcing is particularly sensible when the filing is complex, the team prepares XBRL only occasionally, deadlines overlap with audit and year-end work, or internal reviewers are not familiar with the latest ACRA taxonomy and validation requirements. A specialised provider can bring together mapping, validation, review and filing support, while the company’s finance team focuses on confirming that the output agrees with the approved financial statements.

Why Finance Teams Outsource to BoardRoom

  • Tagging that ACRA accepts: BoardRoom’s accountants have supported more than 1,000 companies through XBRL conversion, so an unusual line item is rarely unusual to them.
  • Validation and amendments are our work: The validation run, review of possible errors, and any amendment round sit with BoardRoom, not with your team.
  • Your role becomes review and sign-off: You check the output against the signed statements rather than build it.
  • The filing and annual return move together: When BoardRoom also acts as your corporate secretary, the XBRL file and the annual return are lodged as one job.

A Practical Decision for Finance Teams

In-house preparation can work well for a straightforward, recurring filing where an experienced preparer has sufficient time, and the company maintains strong review controls. Outsourcing becomes more compelling when the filing is new, complex or time-sensitive, or when internal capability is limited. The objective is not simply to transfer an administrative task. It is to reduce execution risk, improve consistency and free the finance team to concentrate on review, approval and core reporting responsibilities.

BoardRoom supports Singapore companies with XBRL preparation, mapping, validation and filing coordination. If your team is assessing whether to retain the work in-house or outsource it, consider the complexity of the financial statements, the experience of the preparer, available review capacity and the consequences of rework close to the filing deadline. Contact BoardRoom to discuss the scope of your next filing.

Navigating Business Restructuring in Singapore: A Strategic Guide for Corporate Planning

Navigating Business Restructuring in Singapore: A Strategic Guide for Corporate Planning

As business conditions evolve, corporate boards and executive leadership teams across Singapore periodically review their business structures as part of their broader strategic and financial planning. These reviews provide an opportunity to reassess operational performance, capital structures, and group structures.

These reviews may reveal that an existing corporate structure no longer supports future growth, risk mitigation, or value preservation. For companies considering restructuring, Singapore offers several statutory pathways under the Companies Act 1967, the Insolvency, Restructuring and Dissolution Act 2018 (IRDA), and prevailing tax legislation.

The appropriate route depends on the company’s financial position, commercial objectives, stakeholder interests, and tax implications.

Operational Restructuring Without Insolvency

Solvent restructuring can help otherwise healthy groups simplify governance, unlock value, or prepare business units for expansion or divestment.

Internal Reorganisation

An internal reorganisation involves transferring assets, intellectual property, or business units between related entities. Common objectives include isolating higher-risk business activities, aligning operations with regional management structures, and simplifying the group for a more tax-efficient operating model.

Section 210 Scheme of Arrangement

Under the Companies Act 1967, Section 210 enables a solvent company to propose a court-sanctioned compromise or arrangement with its members or creditors. It can support complex exercises such as:

  • Corporate amalgamations: Merging entities within a group to eliminate redundant administrative layers.
  • Share swaps and restructurings: Reorganising equity holdings to facilitate new investments or joint ventures.
  • Takeovers and privatisations: Implementing structured buyouts requiring judicial oversight to bind all stakeholders.

Capital Reduction

Governed by Section 78 of the Companies Act 1967, capital reduction allows a company to reduce its paid-up share capital. This can be used to return surplus capital to shareholders, write off accumulated losses to clean up the balance sheet, or simplify the capital structure ahead of a funding round or strategic exit.

Tax Considerations

Restructuring transactions are rarely tax-neutral. Transfer of assets or shares between related entities can trigger stamp duty liabilities, Goods and Services Tax (GST) exposures, or corporate income tax implications. Early tax planning is essential to identify available statutory reliefs and prevent unintended tax leakages.

Restructuring Under Financial Stress: The IRDA Framework

When financial pressures threaten a company’s viability, the focus shifts from operational efficiency to business rescue and asset preservation. The IRDA provides distressed companies with several mechanisms designed to facilitate restructuring and give viable businesses an opportunity to recover.

Scheme of Arrangement

An IRDA scheme can provide distressed companies with important protections, including:

  • Automatic moratoria: Grants immediate, temporary breathing room by restraining creditors from initiating legal or enforcement actions while the company formulates its proposal.
  • Super-priority rescue financing: Allowing new financing to receive priority status or security over existing creditors.
  • Cross-class cram-down: Allowing courts, where appropriate, to sanction arrangements despite objections from certain creditor classes.

Judicial Management

Judicial management provides an alternative for companies facing severe financial distress, particularly where creditor confidence in existing management has deteriorated. A court-appointed judicial manager assumes control to rescue the business as a going concern or achieve a better outcome through asset realisation than a straight liquidation.

Simplified Insolvency Programme

For eligible micro and small enterprises, the Simplified Insolvency Programme offers a faster, lower-cost route to restructuring debts or winding up operations, subject to prescribed asset and liability criteria.

Voluntary Winding-Up Routes for Solvent and Insolvent Companies

Restructuring can also involve an orderly exit. The appropriate winding-up route depends on the company’s financial health.

Members' Voluntary Liquidation (MVL)

An MVL is designed for solvent entities that have ceased trading, fulfilled their purpose, or are being dissolved for group rationalisation. As a formal process for closing a solvent company, an MVL requires directors to meet specific statutory obligations, including providing a statutory Declaration of Solvency confirming that the company can pay its debts in full within 12 months from the commencement of the winding up.

Creditors' Voluntary Liquidation (CVL)

A CVL applies where a company is insolvent and unable to meet its debts as they fall due. Directors can proactively initiate the process, with a private liquidator appointed to realise assets and distribute proceeds to creditors according to statutory priorities.

Striking Off

For dormant companies that meet the Accounting and Corporate Regulatory Authority’s (ACRA) requirements, striking off can provide a simpler and more economical alternative to formal liquidation. The company must generally have ceased trading, have no outstanding assets or liabilities, and have no ongoing regulatory matters.

Tax Clearance

Before a winding-up is completed, tax matters must be addressed with the Inland Revenue Authority of Singapore (IRAS). This includes reviewing historical filings, unutilised losses and capital allowances, capital reductions, and the treatment of remaining corporate assets. Tax clearance is required before final distributions can be made to shareholders by the liquidator.

Tax and Governance Issues that Drive Route Selection

Selecting a restructuring pathway requires boards to consider more than the immediate commercial objective:

  • Stamp duty: Transfer of shares or immovable property may attract stamp duty. Boards should assess whether statutory relief under Section 15 of the Stamp Duties Act is available.
  • GST implications: Asset transfers create GST liabilities. A properly structured transfer of a going concern (TOGC) may qualify for GST relief, subject to the relevant requirements.
  • Capital and dividend treatment: Though Singapore generally does not tax capital gains, boards must distinguish between a return of capital and a distribution of accumulated profits to prevent unexpected tax exposures for recipients.
  • Employees: Restructuring may require changes to employment arrangements, Employee Share Option Plans (ESOPs), and redundancy processes, with compliance under the Employment Act 1968.
  • Director duties: As a company approaches insolvency, directors must increasingly consider creditor interests. Delaying action or pursuing an inappropriate restructuring route can increase exposure to personal liability for wrongful trading or breaches of statutory duties.

How Boards Evaluate the Right Route

Boards should assess potential restructuring options systematically with their professional advisers:

Assess Solvency

Use the cash flow test to determine whether the company can pay its debts as they fall due, alongside the balance sheet test to assess whether its total liabilities exceed its total assets. These assessments can help determine whether solvent restructuring or an IRDA process is appropriate.

Map Stakeholders

Map out your corporate ecosystem. Balance the competing interests of secured/unsecured creditors, shareholders, employees, customers, and regulators.

Define the commercial objective

Determine whether the priority is business rescue, asset disposal, group simplification, or an orderly wind-up.

Assess Time and Cost

Compare the resources and timelines required for court-supervised processes against simpler administrative routes.

Align Advisers

Coordinate corporate counsel, restructuring, tax, and corporate secretarial advisers to minimise execution delays and unnecessary costs.

Strategic Relevance by Corporate Role

These considerations are particularly relevant to:

  • Boards and chief financial officers (CFOs) reviewing group architecture, capital structures, or operational viability as part of ongoing financial and strategic planning.
  • Private equity (PE) sponsors and shareholders considering exits, recapitalisations, or divestments.
  • Distressed-company directors evaluating rescue, judicial management, or winding-up options.
  • Founders and family shareholders seeking to simplify corporate structures or close dormant entities.

Taking the Next Step in Your Restructuring Journey

Business restructuring requires careful decisions around solvency, stakeholder interests, tax exposure, and execution timing. Selecting the appropriate statutory route can help preserve enterprise value, minimise financial leakage, and manage directors’ regulatory obligations.

As you weigh your options, an experienced corporate services partner can help navigate the process. BoardRoom supports companies in Singapore with corporate restructuring services, including MVL, capital reductions, and corporate secretarial compliance.

Contact our team today to discuss how we can help you structure your business for its next phase of growth.

Case Study: Future-Proofing Enterprise Payroll: How BoardRoom Unified a Global Manufacturer’s Malaysian Payroll

Case Study: Future-Proofing Enterprise Payroll: How BoardRoom Unified a Global Manufacturer’s Malaysian Payroll

Payroll at scale is rarely just a calculation problem. It breaks down at the hand-off points between systems: data that does not flow consistently between human resources (HR) and payroll platforms, attendance records that fail to update in real time, and shift data that arrives too late to be checked properly. In Malaysia, managing statutory contributions – such as the Employees Provident Fund (EPF), the Social Security Organisation (SOCSO), and the Employment Insurance System (EIS) – by the 15th becomes increasingly burdensome as headcount grows.

A global electronics manufacturing services provider reached that tipping point. With its largest Asian operations in Malaysia and a workforce serving regulated and industrial sectors, the company’s payroll operation had reached the limits of its systems. More than 10,000 employees were supported by a process that relied on manual bridging between platforms at each cycle. Employee records sat in a global human resources information system (HRIS), leave and attendance were tracked through an aging in-house system, and payroll ran separately from both.

This case study sets out how BoardRoom enabled the manufacturer to transition from fragmented payroll, leave, and attendance systems to a single integrated platform, and what that change meant in practice for accuracy, employee experience, and payroll oversight.

Client Context and Payroll Environment

The manufacturer employs around 20,000 people globally, with more than half based in Malaysia. Its payroll environment reflected that massive scale, with large headcounts, complex time attendance requirements for both office and production employees, and the need to interface reliably with the HRIS every cycle.

The in-house attendance system had been built on an outdated technology stack and had reached the end of its usable lifespan. The information technology (IT) team was no longer able to support new configurations or enhancements, meaning that requests from HR and operations could not be actioned within the system.

Concurrently, the integration between the HRIS and the payroll system was incomplete. An estimated 20% to 30% of employee data still requires manual HR input to update payroll records each cycle, creating a heavy administrative burden and a recurring risk of data entry errors.

The Friction Points Before The Transition

Before partnering with BoardRoom, the manufacturer faced four operational bottlenecks:

  • Disconnected systems: The HRIS, the in-house attendance platform, and payroll operated independently. Data did not flow reliably between them, and HR teams bridged the gaps through manual effort each payroll cycle.
  • Outdated attendance infrastructure: The in-house system could not support new features or real-time updates, causing errors to accumulate without a reliable mechanism to detect them systematically.
  • No single view of payroll data: Leave, attendance, and payroll were reported from three separate systems, leaving HR without a consolidated view to verify figures before each cycle closed.
  • Limited employee access: Production workers without dedicated workstations relied on shared desktops to submit leave and attendance records, creating delays and contributing to untraceable payroll backlogs.

The Solutions the Manufacturer Required

The company needed a transformation partner rather than a traditional payroll processor. They needed a solution capable of consolidating leave, time attendance, and payroll processing into a single integrated platform, connecting seamlessly with their HRIS, and handling Malaysian statutory requirements at scale, with the flexibility to extend as the business grows.

Ultimately, the manufacturer needed a system and operating model that could remove the manual work that had built up between disconnected platforms, backed by a partner with the in-market expertise to implement and maintain it at scale.

The Strategies Introduced by BoardRoom

BoardRoom Asia’s Head of Payroll Nie Ying, who led the transition implementation, describes the core change:

“We consolidated all modules such as leave, time attendance, and payroll into a single platform. This centralisation allows data to flow seamlessly, meaning updates to attendance or leave are immediately reflected in payroll processing.”

The implementation targeted five key pillars:

  • Unified platform: Leave, time attendance, and payroll were consolidated into Ignite, BoardRoom’s payroll and HR platform, eliminating the need to manage data across separate systems and removing the manual reconciliation previously required at every cycle.
  • HRIS integration: Ignite seamlessly manages employee data interfaces between the payroll system and HRIS, enabling automated and accurate data synchronisation. Furthermore, a scheduled file comparison was established between the HRIS and Ignite at agreed intervals. Any variance in employee data automatically triggered a notification to both the client and BoardRoom for investigation, replacing ad hoc manual checks with automated exception handling.
  • Mobile access: Employees gained mobile access to submit leave and claims, view payslips, and track attendance records. This gave production workers without fixed workstations a direct digital channel and enabled supervisors to receive automated reminders to approve attendance on time.
  • Phased onboarding: A 10-person cross-functional committee drawn from HR, finance, IT, and project management met weekly across a 12-month implementation period. Development proceeded phase by phase, each fully tested before the next began, ensuring that changes were stable before additional complexity was introduced.
  • Ongoing enhancement support: BoardRoom continued to support the manufacturer after go-live with continuous system improvements, operating on an ongoing engagement basis rather than treating implementation as a one-time event.

Impact and Outcomes in Efficiency, Accuracy, and Scale

The transition yielded immediate, measurable improvements across the manufacturer’s operations:

  • Manual data entry eliminated: After migrating to Ignite, the estimated 20% to 30% of HRIS data previously requiring manual updates dropped to near zero. The interface handles the full data flow automatically, freeing HR from a recurring administrative burden.
  • Near-zero system variance: Data discrepancies between the HRIS and Ignite were effectively eliminated. Exceptional cases are surfaced by the automated comparison process and investigated promptly without manual searching.
  • Fewer retrospective adjustments: With employees able to submit attendance and view approval status in real time via mobile, the volume of back-payments and retrospective payroll adjustments dropped significantly.
  • Improved employee experience: Production employees now have direct, mobile access to submit leave, view payslips, and manage attendance from any location. The change in accessibility was one of the most visible improvements for the workforce as a whole.
  • Transition without disruption: Despite the 12-month onboarding timeline, the move to the new platform was completed without major operational disruption. The cross-functional committee structure and weekly cadence allowed requirements to be captured and resolved progressively throughout implementation.

Why BoardRoom Stood Out

Reflecting on the success of the partnership, Nie Ying highlights these defining factors: deep data integration, a single unified platform, and reliable support at scale.

  • Integration depth: Ignite connected with the HRIS and the existing attendance infrastructure, replacing manual data gaps with an automated and auditable flow.
  • Built to scale: The manufacturer now runs its Malaysian payroll on a single platform built to support additional entities and headcount growth without needing to rebuild the operating model.
  • Delivery flexibility: The manufacturer currently outsources payroll fully to BoardRoom. However, if the organisation opts to bring payroll in-house in the future, the Ignite platform can transition to a subscription model, protecting their initial 12-month investment and preserving continuity for employees and HR teams.
  • Proven at scale: The engagement demonstrates BoardRoom’s ability to implement and manage large, complex payroll environments with sophisticated time attendance requirements under a single point of accountability.

Fixing High-Volume Payroll at the Root

Payroll at scale works when the hand-offs between systems are as well-governed as the calculations themselves. Manual bridging may hold at a smaller headcount, but as the workforce grows and HR systems become more interconnected, the gaps between platforms become the primary source of risk and rework.

A partner that can unify those systems, interface with existing HR infrastructure, and sustain the engagement well beyond go-live removes the problem at its source.

BoardRoom delivers managed payroll outsourcing and HR platform services for multinationals operating across Asia. To discuss your payroll operating model, contact the BoardRoom team today.

Payroll Case Study: How BoardRoom Helped a Landmark Hospitality Group Strengthen Payroll Accuracy, Controls, and Reporting at Scale

Payroll Case Study: How BoardRoom Helped a Landmark Hospitality Group Strengthen Payroll Accuracy, Controls, and Reporting at Scale

Processing payroll accurately for more than 10,000 employees within a tight multi-day window requires a flawless upstream process to function reliably. When leave approvals, attendance records, and claims data do not flow automatically into payroll, human resource (HR) teams absorb the shortfall through manual reconciliation. At that scale, manual effort ceases to be an occasional fix and becomes a recurring operational burden that increases risk and drains corporate resources.

One of Singapore’s landmark hospitality and entertainment groups had relied on the same payroll system for more than 10 years. While functional, the system enhancement and release schedule is unable to respond quickly enough to accommodate changes in the company’s organisational structure and business requirements.

Following the Group’s adoption of a new global human resources information system (HRIS), the existing payroll platform was unable to adequately support the evolving integration and interface requirements.

As a result, three separate systems for payroll, leave, and attendance operated independently, and any adjustment required manual reconciliation across all three. The payroll team bore the operational risk of those gaps every month.

This case study describes how BoardRoom helped the enterprise redesign its payroll data flows, automate high-volume manual processes, and build an agile platform that can evolve alongside the business.

Client Context and Payroll Environment

The group runs hotel, retail, food and beverage, and large-scale events operations in Singapore, with a workforce of more than 10,000 employees. The complexity of the operation means that workforce composition, shift patterns, and leave entitlements vary significantly across employee groups.

At this scale, payroll accuracy depends on every element of compensation data flowing into the system within a narrow processing window each month. BoardRoom Asia’s Head of Payroll Nie Ying, who oversaw the implementation, explains the constraint:

“The payroll window doesn’t give you much room. You have a few days to collect the data, check the figures, and process payments. That happens every cycle, without fail. One inaccuracy in that window and employee payments are at risk of being delayed.”

Key Challenges in a High-Volume Payroll Environment

The organisation’s payroll operations were severely constrained by an outdated infrastructure that struggled to keep pace with modern corporate software. The friction between their newly adopted HR systems and a legacy payroll foundation manifested in several operational bottlenecks:

  • Legacy system limitations: Operating on a platform for more than 10 years meant the organisation was trapped in a system the vendor would no longer customise or enhance. This blocked the business from adapting its payroll architecture to shifting regulatory requirements and evolving internal policies.
  • HRIS incompatibility: The organisation had adopted a new HRIS for HR management, but the existing payroll system could not support the interface. Data transfer between HR records and payroll processing became manual by default, adding a recurring reconciliation step to every payroll cycle.
  • Disconnected systems & complex absence tracking: Payroll, leave, and claims operated independently. Because shift-work leave approvals are frequently delayed or retroactively changed in hospitality, HR teams had to manually track and reverse absence deductions. For a workforce of more than 10,000, this meant manually auditing historical records spanning up to six months per individual.
  • Government-paid leave submission: Each month, the organisation manually submitted between 200 and 300 government-paid leave records. Entering each claim individually into the government portal was heavily time-intensive and carried a significant risk of keying errors at volume.

What the Client Needed from a Provider

The client was not seeking a fully outsourced payroll function. The requirement was a system capable of interfacing with the HRIS and with existing third-party leave and attendance platforms, while automating the processes generating the most manual risk and rework.

Flexibility was a key criterion: the solution needed to connect to the group’s existing employee-facing tools without requiring a workforce of more than 10,000 to change how they submitted leave or attendance records. Forcing that change at scale would have created disruption that outweighed the operational gain.

How BoardRoom Delivered

To address these friction points without disrupting their daily operations, BoardRoom introduced an architecture centred on backend automation and deep software compatibility by executing the transition through five targeted pillars:

1. Flexible data architecture

BoardRoom implemented Ignite in a configuration that received daily data feeds from the organisation’s existing leave, attendance and HRIS systems, rather than requiring full module consolidation within the platform. Employees continued using familiar tools while payroll processing was consolidated and automated in the background.

2. Automated absence management

Ignite was configured to detect retroactive leave approvals and reverse absence deductions automatically, regardless of how far back the original deduction had been applied. HR teams no longer need to check individual records or perform manual corrections across months of historical payroll data.

3. Government-paid leave automation

Ignite uses leave data already in the system to generate structured output for Singapore government portals. Monthly government-paid leave submissions moved from individual manual data entry to a single consolidated file upload, saving substantial processing time each cycle.

4. Joint onboarding governance

BoardRoom and the group established a joint committee covering information technology (IT), HR, payroll, and project management. Their internal testing protocols were incorporated into the project plan from the outset and supported by the BoardRoom Singapore team, which made regular in-person visits throughout implementation to maintain progress and address requirements in detail.

Strategic Impact and Outcomes

The deployment of the Ignite platform reshaped how the group manages its monthly payroll lifecycle. It shifted its HR department away from reactive firefighting toward structured oversight. Additionally, the organisation unlocked measurable improvements in corporate speed, accuracy, and compliance:

  • Near-zero manual intervention: The volume of manual HR tasks required to maintain payroll data accuracy has reduced substantially. As Nie Ying notes: “Everything is streamlined and automated.”
  • Elimination of historical rework: Automated absence handling resolved the enterprise’s most tedious bottleneck. Ignite now tracks and reprocesses absence deductions across historical payroll cycles without HR involvement, eliminating a category of rework that previously required individual record-level checking across the entire workforce.
  • Government submission efficiency: Monthly government-paid leave submissions reduced from hundreds of individual data entries to a single consolidated file upload, freeing up significant HR capacity each month.
  • Bulletproof audit trails: Digital approval workflows for bonuses and leave encashment have significantly improved both processing speed and the quality of the audit trail available to finance and HR leadership.
  • Ongoing enhancement capability: BoardRoom continued to support the group with system enhancements following go-live, with query response times typically within a business day. The relationship has evolved past a standard transactional vendor arrangement into a collaborative partnership.

Why BoardRoom Stood Out

BoardRoom stood out because of its technological capabilities of the Ignite platform and its delivery philosophy:

  • System flexibility & adaptability: Ignite’s capacity to integrate with external systems allowed the group to maximise its investment in its HRIS without sacrificing localised payroll precision. The system can be enhanced without replacing the underlying architecture.
  • Responsive support: Nie Ying identifies post-live responsiveness as the clearest differentiator from the group’s previous vendor: “Our framework ensures that no matter what query they bring to us, we are there to immediately assist them. That level of continuous, proactive support didn’t exist in their old system.”
  • Long-term partnership: Implementations of this scale are designed to serve the organisation for decades. BoardRoom’s approach to continuous improvement extends the value of the initial investment well beyond go-live, as the system adapts to new requirements over time.

The Value of Modernising Payroll

Streamlining the payroll infrastructure requires a provider who can navigate around existing digital infrastructure, automate targeted risk areas, and remain accountable long after go-live. By treating payroll as a strategic operational discipline rather than a compliance checkbox, the group successfully eliminated systemic manual risk, unlocked hundreds of productive HR hours, and built a future-proof foundation for growth.

BoardRoom delivers payroll implementation and managed services for large employers across Singapore and Asia. To discuss how BoardRoom can support your payroll operations, contact the BoardRoom team.

Inside the Dividend Distribution Process After an Annual General Meeting

Inside the Dividend Distribution Process After an Annual General Meeting

Shareholders judge a company on what happens after a dividend is approved and not on the resolution itself. The days and weeks following the annual general meeting (AGM) are when distribution quality becomes visible: payments arrive on time, communications are clear, and entitlements are accurate. Alternatively, they may fail.

Bank rejections, outdated payout records, withholding tax inaccuracies, and inconsistencies in entitlement records constitute the primary drivers of shareholder grievances following dividend distributions.

This article delineates the timeline, internal controls, and registrar obligations that ensure the integrity of dividend distributions from the date of declaration through to final settlement.

The End-to-End Dividend Timeline

Before a dividend can be paid, the board must first approve the dividend amount and authorise its declaration. Once approved, the dividend cycle begins, with each milestone creating downstream dependencies that the share registrar and the company must manage in sequence: 

  • Dividend announcement: The company announces the dividend amount and key dates, initiating the distribution process. 
  • AGM approval: Shareholders ratify the final dividend at the AGM, after which the payment cycle is formally activated. 
  • Ex-dividend date: Shares bought on or after this date no longer carry the right to receive the declared dividend. 
  • Record date: The register is frozen at this point to determine which shareholders are entitled to payment. 
  • Payment date: Funds are disbursed to entitled shareholders through the approved payment channels. 


Throughout this process, Singapore Exchange (SGX) listed companies must ensure that entitlements for both Central Depository (CDP)-held and scrip-held shares are accurately reconciled and validated. On the payment date, distributions are released separately by CDP and the share registrar based on their respective shareholder records.

Setting the Record Date

The record date determines every downstream entitlement calculation. A misalignment at this stage creates disputes with shareholders who have recently bought or sold shares, particularly where settlement timing intersects with the ex-dividend window.

Before the record date is announced, the registrar, the company, and SGX, where applicable, must agree on the date and confirm it against the broader corporate calendar. Changes after the announcement carry significant reputational and regulatory risk and should be treated as a failure of pre-planning rather than an operational adjustment.

Building the Entitlement List

Constructing an accurate entitlement list requires reconciling three data sources:  

  • CDP holdings 
  • Scrip shareholder register 
  • Any corporate action adjustments implemented since the preceding record date 


Edge cases demand specific handling protocols, as errors at this stage propagate through every subsequent step: 

  • Joint holders: Entitlement and payment instructions must reflect the correct account designation and nominated payment channel for each joint holding. 
  • Deceased shareholders: Dividend entitlements are determined based on the shareholder register as at the record date, and payments are made to the names recorded on the register. 
  • Beneficial ownership disclosures: Custodian-held shares require accurate beneficial ownership records to ensure correct entitlement allocation. 


The entitlement list undergoes a pre-payment cross-check for transfers registered around the record date before the payment file is finalised.

Channels, Failures, and Electronic Overhaul of Payment Mechanics

Most shareholders receive payment through direct credit to a registered bank account. However, Singapore’s evolving financial infrastructure has fundamentally altered how non-direct disbursements are handled: 

  • Direct credit: The most efficient channel for CDP-linked and scrip shareholders with current bank account records on file. 
  • Currency selection: Overseas shareholders may be entitled to payment in a currency other than Singapore dollar (SGD), requiring an additional conversion and routing step. 
  • Corporate cheque phase out: Following mandates by the Monetary Authority of Singapore (MAS), banks have ceased issuing corporate cheque books, and all SGD corporate cheques will completely cease processing by 1 January 2027. 
  • Digital alternatives: To replace legacy post-dated cheques, issuers and registrars are transitioning to Electronic Deferred Payment (EDP) systems through major local digital banking platforms, thereby eliminating dependencies on physical paper. 


Payments that fail are managed through a structured suspense protocol. Instances involving bank rejections or unmapped electronic tokens are documented and proactively pursued within a designated timeframe. Any balances that remain unclaimed beyond this established period are subsequently escalated in strict accordance with relevant statutory obligations. 

Understanding the Tax and Statutory Communications

Under the one-tier corporate tax system administered by the Inland Revenue Authority of Singapore (IRAS), dividends paid by resident companies are tax-exempt in the hands of shareholders. This eliminates shareholder-level dividend tax obligations for most domestic distributions.

However, non-resident shareholders are subject to distinct withholding tax considerations contingent upon their residency status and the provisions of applicable tax treaties. The misclassification of a shareholder’s residency status results in erroneous tax treatment, necessitating retrospective adjustments that generate significant administrative and reputational risk.

Dividend vouchers and tax advice are issued to shareholders following payment to support their personal tax records and year-end filing obligations.

Reducing Friction in Shareholder Communications

A clear communications plan significantly reduces inbound queries during the payment window. Pre-payment notifications should confirm: 

  • The dividend amount per share 
  • The expected payment date 
  • The specific electronic payment channel or EDP designation through which each shareholder will receive funds 


Dividend vouchers and accompanying explanatory materials should be written in plain language. Most repeat queries following a distribution cycle arise not from payment errors, but from vouchers and digital notifications that shareholders cannot interpret.

Common Errors in Dividend Distribution

Three categories of error account for the majority of failed or disputed dividend payments: 

  • Stale shareholder data: Outdated bank account records, unlinked digital proxies, or missing tax classification forms cause most failed direct credits and electronic transfers. Regular register hygiene and proactive data updates between distribution cycles are vital to maintaining seamless electronic clearing. 
  • Misclassified holders: Incorrect residency or beneficial ownership classification leads to incorrect tax treatment, which requires post-payment correction and may attract regulatory attention. 
  • Late stakeholder notification: Delayed notice to CDP or SGX compresses the timeline for the entire distribution cycle and increases the risk of errors at each subsequent stage.

Control Framework Before Payment Release

No payment file should be released without completing three control steps: 

  • Maker-checker sign-off: Two-person review and approval of the finalised entitlement list before the payment file is generated or submitted to the clearing bank. 
  • End-to-end reconciliation: The entitlement list, payment file, and bank confirmation are reconciled against each other before and after the payment run to confirm that total amounts and individual entitlements match. 
  • Audit trail retention: Post-payment reports, electronic transaction logs, amendment records, approvals, and supporting correspondence are retained in a documented format to support audit review and shareholder dispute resolution. 

Streamlining Post-AGM Distributions via BoardRoom’s Smart Investor Portal (BSIP)

Exploring a cashless dividend cycle requires a central hub to manage investor data and mitigate transaction failures. BoardRoom’s Smart Investor Portal (BSIP) bridges the gap between the conclusion of your AGM and the final payment run by shifting administrative tracking to a seamless and user-centric ecosystem. 

The platform empowers shareholders to directly manage their bank credentials, update digital proxies, and register multinational currency preferences online. This automated self-service model eliminates the risk of stale registry data and removes manual paper tracking for physical certificate holders. Companies dramatically reduce the post-meeting surge of inbound inquiries while giving investors instant and transparent visibility into their payout status by creating a unified digital bridge.  

Discover how the system simplifies investor onboarding and distribution tracking by connecting with our registry specialists, and consider deploying BSIP today.

Dividend Distribution as a Controls Discipline

Reliable dividend distribution protects shareholder confidence and reflects directly on the company’s operational credibility. Strong record reconciliation, robust digital payment controls, and clear communications prevent the disputes and delays that erode trust between limited companies and their shareholders. 

BoardRoom’s share registry services support SGX-listed companies and unlisted issuers across the full dividend distribution cycle, from entitlement list preparation through to payment, tax communications, and post-distribution reporting. 

For companies seeking integrated support across AGM administration and post-meeting compliance, BoardRoom’s corporate secretarial services provide the governance infrastructure that supports each stage of the corporate calendar. Reach out to our team today to review your next distribution cycle.

What Members’ Voluntary Liquidation Demands of a Solvent Company

What Members’ Voluntary Liquidation Demands of a Solvent Company

For corporations and group finance teams operating across Southeast Asia, winding up a solvent business entity requires a highly systematic approach to regulatory compliance. A members’ voluntary liquidation (MVL) offers an orderly, legally secure method to dissolve a company, distribute remaining capital to shareholders, and close tax obligations definitively.

This guide breaks down the essential statutory frameworks, step-by-step procedures, and common compliance pitfalls within Singapore and Malaysia. By fully understanding the legal responsibilities associated with solvency declarations and anticipating regional tax clearance timelines, corporate boards can safeguard themselves against personal liability while ensuring a streamlined corporate wind-up.

Why Winding Up Requires Higher Discipline Than Directors Expect

Initiating an MVL appears straightforward on paper. Corporate boards frequently view closing a solvent entity as a simple administrative formality, assuming the absence of insolvency eliminates operational friction. In practice, corporate wind-ups routinely stall during critical phases such as solvency declarations, statutory tax clearance, and asset realisation across both Singapore and Malaysia. The process demands a rigorous level of regulatory compliance that catches numerous business leaders unprepared.

Directors often underestimate the significant personal liability attached to a statutory declaration of solvency. Additionally, they frequently overlook the extensive operational work required between the initial board resolution and final dissolution. Far from being a mere paper exercise, a formal voluntary liquidation represents a tightly regulated legal procedure.

When MVL is the Right Route

Corporate entities require a structured exit mechanism when their commercial utility ceases. An MVL serves as the standard legal pathway for several specific business scenarios:

  • Solvent winding-up: This route is appropriate when a company maintains sufficient assets to pay its debts in full within a maximum period of 12 months, and shareholders agree to cease operations.
  • Group simplification: Holding companies deploy this strategy to dismantle dormant subsidiaries, eliminate redundant administrative layers, and restructure regional entities to optimise operational efficiency.
  • Strike-off comparison: Winding up differs significantly from simpler options. While a strike-off application suits dormant entities with zero liabilities and no remaining assets, it lacks structural robustness. It does not provide the identical legal finality or shareholder distribution mechanism inherent in a formal winding-up proceeding.

Choosing between a strike-off and liquidation depends heavily on balance sheet complexity. For entities holding significant undistributed capital or intellectual property, closing via liquidation provides a legally binding resolution. Winding up represents the definitive choice for ensuring complete company dissolution, which regulators recognise as legally unassailable.

Statutory Basis in Each Market

The cross-border regulatory frameworks of Singapore and Malaysia share historical origins, yet operate under distinct modern statutes.

  • In Singapore: An MVL is governed by the Insolvency, Restructuring and Dissolution Act 2018 (IRDA) alongside provisions of the Companies Act 1967. To initiate the process, directors must execute and file a formal declaration of solvency under Section 163 of the IRDA. Winding up via this method ensures that a voluntary liquidation conforms strictly to local corporate governance expectations.
  • In Malaysia: The corporate ecosystem regulates this process through the Companies Act 2016. Under Section 443, a majority of directors must sign a written declaration of solvency. This instrument confirms that the board has conducted a thorough inquiry into the company’s affairs and concluded that the entity can settle all outstanding debts within 12 months from the commencement of the winding-up. Compliance with these rules is central to executing a lawful voluntary liquidation.

The core underlying principle remains identical across the two markets. Both jurisdictions impose severe personal criminal liability on directors who execute declarations without possessing reasonable grounds.

The Declaration of Solvency

The declaration of solvency represents the foundational legal pillar of the winding-up process. Directors must back this requirement with verifiable financial realities. To ensure full compliance and protect corporate officers, boards must carefully navigate several critical components of this statutory requirement:

  • Supporting evidence: A robust suite of financial documentation must support the formal declaration. Boards must review a current balance sheet compiled at the closest practicable date, an exhaustive contingent liability review, and a detailed 12-month cash flow projection. These documents provide the objective justification that all creditors will be paid in full.
  • Regulatory timing: In Singapore, directors must lodge the declaration with the Accounting and Corporate Regulatory Authority (ACRA) prior to the date on which shareholders pass the resolution to wind up. In Malaysia, the executed declaration must be submitted to the Companies Commission of Malaysia (SSM) under Section 443 requirements before dispatching notices for the extraordinary general meeting to commence winding-up and appointment of liquidator.
  • Personal exposure: Failure to exercise due diligence carries harsh penalties. If a company is wound up and debts remain unpaid within the designated year, courts maintain a presumption that the director lacked reasonable grounds. Directors who sign without proper evidentiary support remain personally exposed to fines or imprisonment.

The Process from Resolution to Dissolution

The transition from an active business to a dissolved entity follows a structured chronological sequence, managed by a professional liquidator, that must be executed without error to achieve a clean closure:

  • Special resolution: Shareholders pass a special resolution to wind up the entity voluntarily, an action that transfers operational control to an appointed liquidator.
  • Asset realisation: The liquidator assumes management control, settling outstanding creditor claims, realising corporate assets, and obtaining tax clearance from relevant revenue authorities.
  • Final meeting: Upon completing distributions, the liquidator calls a final general meeting of members to present the account illustrating how the winding-up was conducted.
  • Dissolution: The liquidator lodges final returns with the appropriate registrar (ACRA or SSM), triggering the final dissolution clock after the prescribed statutory waiting period.

The Tax Clearance Bottleneck

Securing formal tax clearance represents the single most protracted step in the winding-up timeline, consuming greater time than all other operational phases combined.

  • In Singapore: The Inland Revenue Authority of Singapore (IRAS) reviews final corporate tax filings, ensures proper Goods and Services Tax (GST) deregistration, and verifies outstanding obligations.
  • In Malaysia: The Inland Revenue Board of Malaysia (LHDN) scrutinises final tax computations, reviews withholding tax positions, and demands comprehensive supporting accounting schedules.

To expedite this intensive process, companies must engage in meticulous upstream preparation. Maintaining immaculate historical tax records and ensuring complete documentation significantly shortens the clearance window in both jurisdictions. Engaging professional corporate secretarial services remains critical to navigating these regulatory reviews successfully.

Realistic Timeline Expectations for MVL

A clean winding-up typically requires 12 to 18 months to achieve complete closure in both markets. While shareholders expect a rapid distribution of capital, several common factors cause timelines to slip:

  • Incomplete or poorly maintained corporate or accounting records from prior financial years
  • Unresolved intercompany balances and complex cross-border parental debts
  • Delays in obtaining final clearance certificates from tax authorities
  • Contingent liabilities were discovered late in the process
  • Unresolved contractual obligations
  • Delays in closing bank accounts and remitting residual balances
  • Outstanding claims or disputes
  • Unresolved employee matters, including final salary, EPF/SOCSO/PCB or CPF contributions and termination documentation

To compress these intervals, experienced liquidators run multiple workstreams concurrently. Asset realisation, tax clearance preparations, and creditor settlement processes should be executed in parallel to minimise structural delays.

Catching MVL Errors to Avoid Liability

The winding-up process contains several regulatory pitfalls that can expose corporate officers to unexpected vulnerabilities:

  • Premature distribution: Distributing corporate assets to shareholders before completely settling creditor liabilities and obtaining formal tax clearance certificates creates immediate personal exposure for directors.
  • Underestimating governance: Treating the process as an elementary form-filling exercise rather than a regulated statutory mechanism leads to compliance errors that invariably surface during tax clearance audits.
  • Group corporate oversights: Forgetting transfer pricing documentation or failing to formalise intercompany debt forgiveness during complex group wind-ups can derail restructuring plans.

Organisations must prioritise robust governance by collaborating with established liquidation and winding-up specialists to ensure every transaction withstands regulatory audit.

Who Should Choose the MVL Route

Executing a structured, formal wind-up is highly beneficial for specific corporate stakeholders seeking risk mitigation and clean structural closures:

  • Directors planning a winding-up: Corporate boards overseeing solvent entities in Singapore or Malaysia preparing to cease operations over the coming 12 to 24 months.
  • Group finance teams: Regional financial officers tasked with removing redundant, dormant subsidiaries across Southeast Asia to reduce ongoing compliance overheads.
  • Shareholders preparing for exit: Investors and founders planning a clean corporate exit, business sale, or strategic corporate restructuring that requires a flawless distribution of wealth.

Mitigating Exit Risks Through Professional Liquidation Management

MVL represents an intensive exercise in corporate governance and tax compliance rather than a simple form-filling exercise. Robust upstream preparation, orderly asset management, and meticulous bookkeeping protect directors from personal exposure while reducing the time required to achieve finality in both Singapore and Malaysia.

Navigating these statutory intricacies requires specialised professional guidance. The professional teams at BoardRoom advise enterprises across both markets on solvent wind-up strategies, expert liquidator coordination, and comprehensive tax compliance management. For organisations seeking a seamless transition, partnering with our corporate advisory experts ensures that your business exit satisfies every regulatory demand.

Contact BoardRoom today to evaluate your corporate wind-up objectives and ensure a legally compliant transition.

Payroll Outsourcing in Singapore: How to Evaluate Providers, Manage Onboarding, and Run a Smooth Parallel Test

Payroll Outsourcing in Singapore: How to Evaluate Providers, Manage Onboarding, and Run a Smooth Parallel Test

Payroll outsourcing represents a significant strategic shift for any Singapore-based organisation. However, the success of this transition depends on vendor selection and quality of the implementation and handover. When payroll transitions fail, the root cause is often due to fragmented communication and poor execution during onboarding.

Even with a reputable provider, risks such as weak onboarding structures, unclear internal policies, poor data quality, and compressed testing timelines can disrupt operations.

This guide provides a practical framework for evaluating providers, preparing for onboarding, and executing a structured parallel test to ensure long-term stability. Organisations exploring this transition may benefit from understanding how payroll outsourcing services in Singapore work in practice.

When Payroll Outsourcing Makes Sense

It is important to understand when outsourcing becomes a practical solution before evaluating providers.

As organisations grow, managing diverse pay elements, variable commissions, and layered benefits becomes increasingly complex. Payroll outsourcing transforms this administrative burden into a scalable process, allowing leadership to maintain visibility over labour costs without expanding internal human resources or finance teams.

Beyond efficiency, outsourcing provides access to specialised compliance expertise. Singapore’s employment and tax regulations are subject to frequent updates, and errors can result in penalties. Professional providers ensure accurate handling of Central Provident Fund (CPF) contributions and statutory filings, allowing organisations to operate with greater confidence.

Outsourcing also reduces “key person dependency,” ensuring that a sudden resignation from a single internal payroll officer will never jeopardise your entire monthly payroll cycle.

Which Organisations Benefit Most?

Payroll outsourcing is most beneficial for organisations that have:

  • Multi-country operations requiring compliance with different labour and tax regulations.
  • Large or growing workforces with high payroll transaction volumes.
  • Complex payroll requirements, such as overtime, shift allowances, commissions, and statutory reporting.
  • Limited in-house payroll expertise or HR resources.
  • Business transformation initiatives, including mergers, acquisitions, or system migrations.

By outsourcing payroll, these organisations can improve compliance, reduce administrative workload, minimize payroll risks, and allow HR teams to focus on strategic business priorities rather than payroll processing.

What Payroll Outsourcing Covers in Singapore

In the local context, payroll outsourcing extends beyond basic salary processing. A comprehensive service scope typically includes:

  • Salary and Statutory Calculations: Accurate computation of gross-to-net pay, including CPF contributions and Skills Development Levy (SDL).
  • Compliance and Submissions: Timely payslip distribution and statutory filings, including government-paid leave claims.
  • Tax Integration: Support for Inland Revenue Authority of Singapore (IRAS) requirements, including the Auto-Inclusion Scheme (AIS).
  • Flexible Scope: Customised arrangements depending on whether services include employee queries or expense reimbursements.

Clearly defining the responsibilities is essential. Organisations must determine whether the provider manages the full payroll process or if internal teams retain approval authority. Establishing these boundaries early ensures compliance with Ministry of Manpower (MOM) regulations and prevents operational gaps.

How to Evaluate Payroll Service Providers

A thorough evaluation should go beyond pricing and focus on operational capability. Key areas to assess include:

  1. Compliance Expertise: The provider should demonstrate strong knowledge of local labour laws, tax requirements, statutory submissions, payroll deadlines, and country-specific regulatory changes.
  2. Accuracy and Timeliness: Payroll must be processed correctly and on schedule, with clear quality checks, validation controls, and error resolution procedures.
  3. Data Security and Confidentiality: The provider should comply with data protection regulations and hold certifications such as ISO 270001, SOC 1 or SOC 2.
  4. Client Support and Responsiveness: A strong provider should offer a dedicated service team, clear escalation channels, timely response standards, and proactive communication during payroll cycles.
  5. Business Continuity and Risk Management: Assess the provider’s business continuity and disaster recovery capabilities, including backup processing arrangements, Recovery Time Objectives (RTOs) for restoring payroll operations, Recovery Point Objectives (RPOs) for data recovery, regular testing, incident management procedures, and overall risk management framework to ensure uninterrupted payroll operations during disruptions.

Recommendation: The best payroll service provider is not necessarily the lowest-cost option, but the one that can reduce compliance risk, protect employee data, improve payroll accuracy, and provide reliable support as the business grows.

The Onboarding and Data Preparation Phase

Inaccurate master data is the primary cause of onboarding delays. A successful implementation requires extensive internal data cleansing across two critical steps: a Discovery Phase to align the project scope and unique policies, followed by a Configuration Phase in which operational rules are programmed into the system.

To maintain momentum, establish fixed data cut-off dates and frequent validation checkpoints early. Internal teams must audit and clean these four core data pillars before configuration concludes:

  • Employee Master Data: Ensuring National Registration Identity Card (NRIC) or Foreign Identification Number (FIN), addresses, and bank details are current.
  • Pay Element Mapping: Defining which components of a salary package are CPF-attractable or taxable.
  • Historical Data: Compiling year-to-date (YTD) figures to ensure accurate tax reporting at the end of the calendar year.
  • Approval Hierarchies: Establishing exactly who is authorised to sign off on various stages of the payroll cycle.

How to Run a Useful Parallel Test

The parallel test is a critical phase where the new system runs alongside the existing process to identify discrepancies. Best practices include:

  • Classifying Mismatches by Severity: Minor rounding differences may be acceptable, but discrepancies in CPF or net pay must be resolved
  • Maintaining a Reconciliation Log: Tracking whether issues stem from system configuration or data errors

Final sign-off for “Go-Live” should only be granted once both runs produce identical results for at least two consecutive payroll cycles. Reaching this milestone marks the formal decommissioning of your legacy workflow and establishes the outsourced service as your primary system of record for salary payments and statutory filings.

For deeper operational assurance, look to the internal audit standards provided by the Institute of Singapore Chartered Accountants (ISCA) to help structure your final payroll reviews.

Common Issues that Cause Delays or Rework

Even with a capable provider, internal challenges can delay implementation, which includes:

  • Inconsistent payroll rules across departments.
  • Unclear ownership of payroll data between HR and finance.
  • Late submission of employee data after the cut-off dates.

Resolving these ambiguities requires a robust governance framework that defines a “Single Source of Truth.” When roles are clearly demarcated through a Data Responsibility Matrix, the payroll services partner receives cleaner inputs, resulting in faster processing and fewer manual interventions.

Establishing this accountability early in the implementation phase prevents the erosion of trust between the organisation and the service provider.

Key Questions to Ask Before Signing Off on Go-Live

The decision to transition to an external partner necessitates a rigorous verification of the provider’s operational resilience. Organisations must ensure that the proposed workflows offer higher levels of security and accountability than a standard in-house payroll system. This scrutiny serves as a final safeguard, confirming that the partnership is equipped to manage the nuances of the Singaporean regulatory environment without disruption.

Before transitioning fully, organisations should confirm the following:

  • Exception Handling: Procedures for terminations or retroactive adjustments.
  • Process Validation: Evidence supporting the provider’s maker-checker controls.
  • Tax Compliance: Alignment with AIS requirements.
  • Scalability: Ability to support business growth or structural changes.

These checks ensure operational readiness and reduce the likelihood of post-launch issues.

Achieving Operational Excellence through Payroll Outsourcing

Successful payroll outsourcing depends on disciplined implementation rather than vendor selection alone. Organisations that invest in proper data preparation, structured onboarding, and rigorous testing build a strong foundation for long-term efficiency and compliance.

With clear governance, accurate data, and effective communication, payroll becomes a reliable background function rather than a recurring operational risk.

For organisations seeking to streamline their back-office processes, BoardRoom offers comprehensive payroll services and a proprietary system designed for the Singapore regulatory environment. Contact our specialists to learn how a managed solution can support your organisation.