Changing Your Company Secretary in Singapore: A Guide to a Smooth Transition

Changing Your Company Secretary in Singapore: A Guide to a Smooth Transition

The company secretary plays a central role in maintaining statutory registers, managing corporate records, and tracking filing deadlines. When a company changes its secretary or corporate secretarial provider, a poorly managed handover can create a gap in responsibility, particularly between the outgoing secretary’s departure and the incoming secretary’s first review.

The risk is self-evident. If both parties assume the other is handling a particular filing, a filing deadline can be missed even when the company has otherwise maintained a clean compliance record.

This article explains when companies typically switch secretaries, what to prepare, how the handover works, and which controls can help prevent missed filings.

When Companies Decide to Switch

Companies typically change their company secretary for one of three reasons. Understanding the reason for the switch helps the incoming company secretary identify the most immediate priorities and address any outstanding matters effectively:

  • Service issues: Late filings, unexplained penalties, or slow responses to routine queries may indicate that a change in company secretary is necessary. In some cases, these issues persist for an extended period before a missed deadline ultimately prompts the switch.
  • Growth and complexity: Changes such as the admission of new shareholders, group restructuring, regional expansion, or plans for a public listing may require a higher level of corporate secretarial support than a provider serving a simpler corporate structure can offer.
  • Cost and continuity: Companies may choose to consolidate their secretarial function with other corporate service providers to achieve greater efficiency. A change may also be required where an individual company secretary resigns, retires, or is otherwise unable to continue in the role.


Whatever the trigger, the switch itself need not give rise to compliance risks. A well-planned handover can address potential gaps before they develop into compliance issues.

What to Prepare Before the Handover

A smooth transition starts with ensuring that the necessary records and information are available and up to date. Preparing these materials before the handover provides the incoming secretary a clear understanding of the company’s current compliance position, governing practices, and upcoming obligations.

  • Register inventory: Statutory registers, including the register of members, directors, charges, and registrable controllers should be complete, accurate, and readily available for review.
  • Filing calendar: Key filing deadlines, including the next annual return and any other pending lodgements with the Accounting and Corporate Regulatory Authority (ACRA) should be identified and documented. This should include matters and filings already in progress with the outgoing secretary.
  • Corporate records: The company’s business profile, constitutional documents, minutes and resolutions, statutory records, and relevant appointment and resignation documents including consent to act as director or company secretary should be organised and made available to the incoming secretary.


This preparation enables both parties to establish a clear understanding of what has been completed, what remains outstanding, and where responsibility sits on the handover date. Clear accountability at the point of transition helps reduce the risk of missed filings, overlooked obligations, and unnecessary compliance issues.

The Handover Steps and Statutory Filings

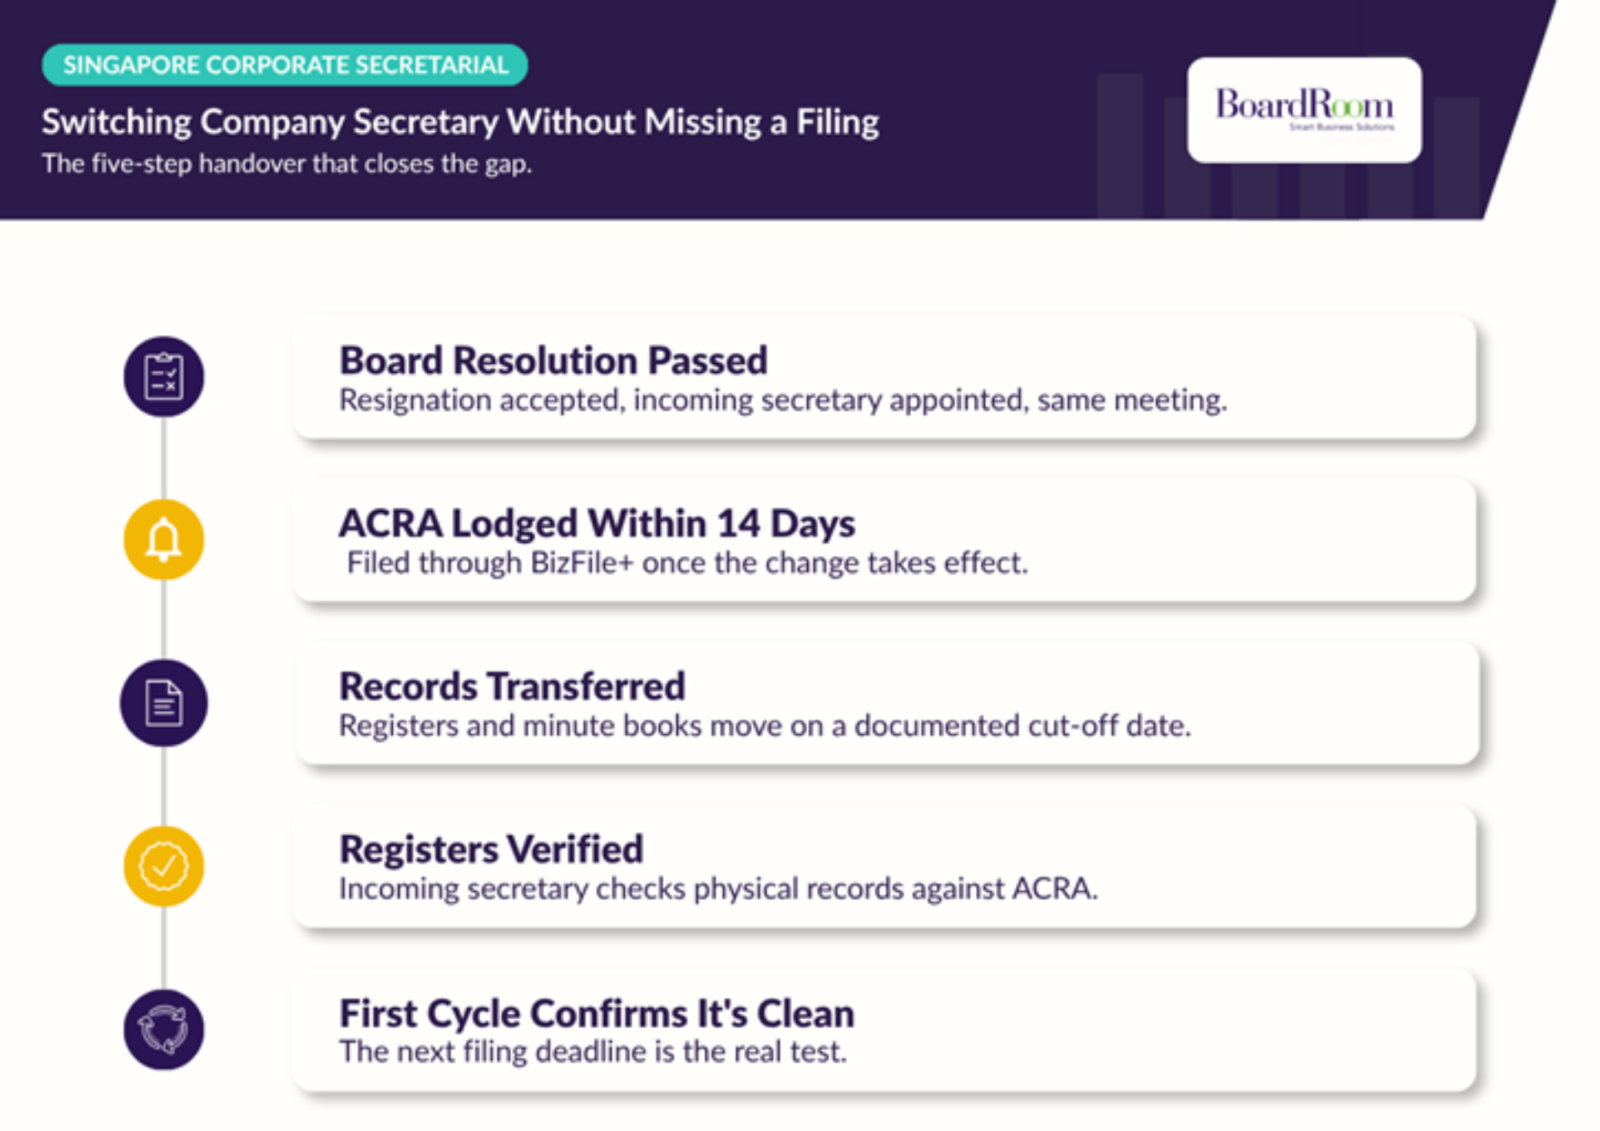
A company secretary transition involves both the formal change of appointment and the transfer of records, information and ongoing responsibilities. Careful coordination of these steps helps ensure continuity and minimise the risks of missed deadlines and compliance gaps:

  • Board resolution: The board should accept the outgoing secretary’s resignation and approve the appointment of the incoming secretary, ideally at the same board meeting to ensure a seamless transition.
  • ACRA lodgement: Changes relating to company officers, including the appointment or cessation of a company secretary, must be lodged with ACRA via BizFile+ within 14 days of the effective date of the change.
  • Records transfer: Statutory registers, minute books, corporate records, and other records are transferred based on the agreed cut-off date. The scope of the handover and the date on which responsibility passes to the incoming company secretary should be clearly documented.
  • Verification and reconciliation: The incoming secretary should review the company’s records against the information maintained by ACRA and identify any discrepancies, incomplete filings, or outstanding compliance matters requiring the follow.


A clearly documented handover process provides certainty on the allocation of responsibilities during the transition period. This helps ensure that ongoing filings, statutory deadlines, and governance obligations continue to be monitored and addressed without interruption.
Risks and Controls During the Transition

The period during a company secretary transition is often where accountability can become less clear. Three simple controls can help protect the company during this time:

  • Clear ownership: Every filing or corporate action due during the transition period should have a named person responsible for completing it. This should be confirmed before the outgoing company secretary ends its engagement.
  • Deadline verification: The incoming secretary should independently verify all upcoming filing deadlines and statutory obligations rather than relying solely on the information including outgoing company secretary’s calendar. This serves as an important safeguard against incomplete records and overlooked deadlines.
  • Record reconciliation: Any discrepancies between the company’s statutory records and the information maintained by ACRA should be identified and resolved as part of the transition process, rather than being deferred until the next filing cycle.


The Singapore Companies Act 1967 requires every company to have at least one company secretary and provides that the office of company secretary must not remain vacant for more than six months. Accordingly, the outgoing company secretary’s cessation and the incoming company secretary’s appointment should be carefully coordinated to ensure continuity of oversight and minimise compliance risk.

A Realistic Timeline for a Smooth Transition

Most company secretary transitions follow a broadly similar pattern, although the timeline will depend on the quality, completeness, and accessibility of the company’s records.

  • Preparation: Allow approximately one to two weeks to gather records, review statutory registers, reconcile outstanding matters, and identify upcoming filing obligations. Additional time may be needed if records are incomplete, inaccurate or outdated.
  • Formal transition: Once responsibilities, records, and outstanding matters have been confirmed, the necessary board resolutions can be passed and the relevant changes lodged with ACRA.
  • Stabilisation: Following the handover, the incoming secretary assumes responsibility for the compliance calendar and oversees the first reporting and filing cycle under the new arrangement. This helps identify any gaps and address any issues that may not have been apparent during the initial review.


While the exact timeline will vary from one company to another, the underlying principle remains the same. The more complete the records are before the transition, the smoother the transition and more effective the handover is likely to be.

A well-managed transition not only facilitates compliance continuity but also gives the incoming company secretary a solid foundation from which to support the company’s ongoing governance and regulatory obligations.

How BoardRoom Manages the Transition

BoardRoom’s corporate secretarial services are structured to minimise the compliance and operational risks that can arise during a company secretary transition:

  • Structured onboarding: A review of statutory register, a documented cut-off date, and a verified filing calendar are established at the outset of the engagement, providing clarity on the company’s current position and upcoming obligations.
  • Clear deadline ownership: Every filing due during and after the handover is assigned in writing before the transition takes effect.
  • Integrated support: Corporate secretarial services are coordinated with accounting, tax, and share registry services where the company’s structure requires it.

A Clean Handover Keeps Compliance on Track

Transitioning to a new company secretary should not disrupt your compliance obligations. The key is to approach the transition as a structured handover, supported by complete records, clear accountability, and a verified filing calendar.

With the proper preparation, the incoming secretary can take over with a clear understanding of the company’s statutory records and upcoming filing obligations, reducing the risk of missed filings, incomplete filings, and unresolved discrepancies that could otherwise affect the company’s compliance position.

BoardRoom supports Singapore companies throughout the company secretarial transition process, from initial review of statutory records and handover planning to ongoing corporate secretarial and compliance management.

If you are considering a change of company secretary, BoardRoom can help assess your current arrangements, coordinate the handover process, and ensure a seamless transition with minimal disruption to your compliance obligations.

Contact BoardRoom to discuss your requirements and plan your transition.
Retrenchment in Singapore: What Employers Must Get Right on Final Pay, Notice, and Statutory Obligations

Retrenchment in Singapore: What Employers Must Get Right on Final Pay, Notice, and Statutory Obligations

Restructuring has picked up across Singapore in 2026. Retrenchments rose from 3,830 in the first quarter to 4,500 in the second quarter, according to the Ministry of Manpower’s (MOM) advance estimates, with most attributed to business reorganisation or restructuring in sectors such as Information & Communications and Manufacturing.

Business closures have also increased. The Accounting and Corporate Regulatory Authority (ACRA) recorded 42,741 business cessations in the first eight months of 2026, 8.5% more than in the same period of 2025. When a restructuring or closure involves letting employees go, managing workforce transition lands on the payroll team.

This places significant time pressure on payroll teams. Final pay, notice, and benefit calculations must be accurate even when deadlines are tight, because an error becomes harder to fix once termination letters have been issued. A routine payroll error can be corrected in the next cycle, but a retrenchment error may not be discovered until after the employee has already left.

The reputational risk is just as high. Errors in final payments affect departing employees, while remaining staff will also notice how the process is handled. The exercise reflects how the organisation treats its people under pressure, not just whether the numbers are correct.

This article covers the employer obligations that apply during retrenchment, how to calculate final pay correctly, the statutory submissions that must not be missed, and where outsourced payroll support can reduce the risk of errors.

When Retrenchment Triggers Employer Obligations

Retrenchment is the dismissal of an employee due to redundancy or business reorganisation. It is distinct from termination for misconduct or resignation, and it matters because it determines which obligations apply and whether the employee may be entitled to a retrenchment benefit.
Employers should not characterise a redundancy as another form of termination simply to avoid retrenchment obligations. The circumstances surrounding the termination may be examined if the exercise is challenged.

These key obligations include:

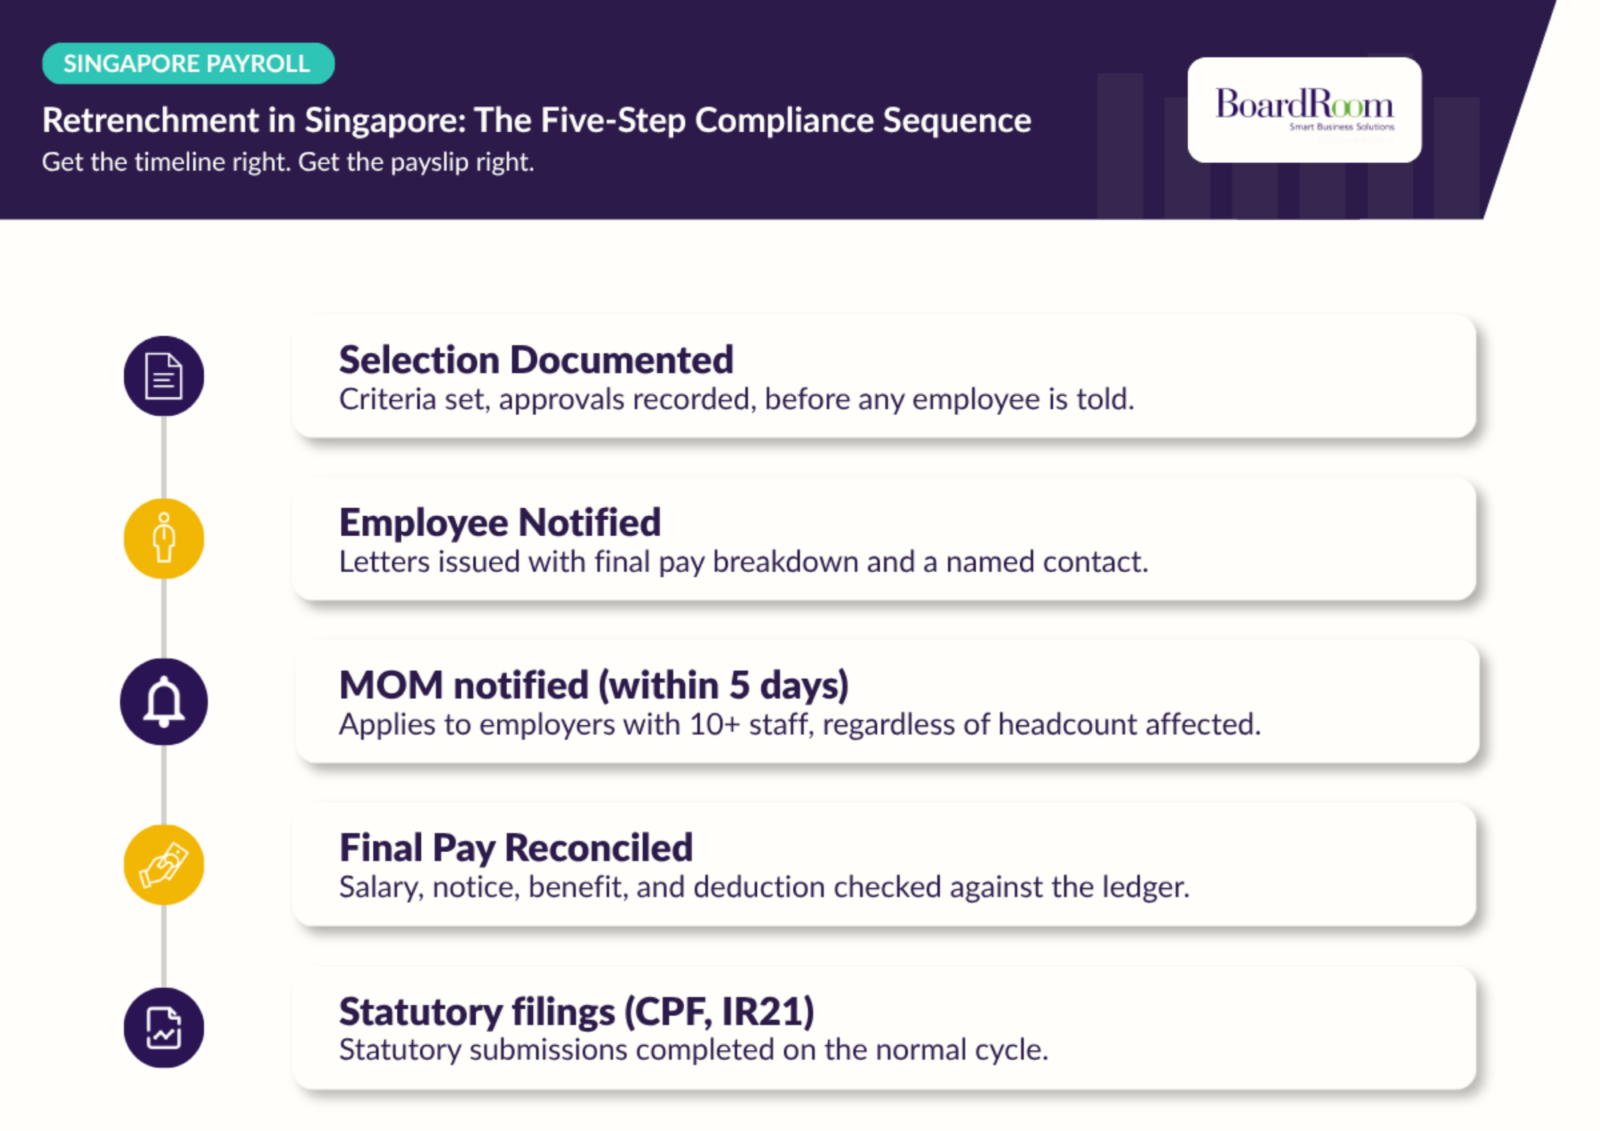
  • Notification duties: Employers with at least 10 employees must notify the Ministry of Manpower (MOM) within five working days of informing affected employees of their retrenchment. This applies even if only one employee is affected. Employers with less than 10 employees are not required to but are strongly encouraged to notify MOM of retrenchment.
  • Fair selection: Selection criteria should be objective, non-discriminatory, and based on factors such as the employee’s ability to contribute to the company’s future business needs. Employers should document the criteria before affected employees are notified, in line with the Tripartite Advisory on Managing Excess Manpower and Responsible Retrenchment.
  • Maintaining a strong local core: Employers should take a long-term view of their manpower needs and ensure that retrenchment exercises do not disproportionately affect local employees. This is among the factors considered by MOM when reviewing retrenchment notifications.

Building the Final Payment Correctly

Final pay consists of several components, each with its own calculation and compliance requirements. Getting these right before payment is easier than fixing an incorrect settlement after the employee has left.

  • Salary to the last day: This includes salary earned up to the employee’s last day of employment, unused annual leave, and any outstanding claims owed to the employee. MOM states that these salaries should be paid on the last day of work for retrenchment.
  • Notice pay: The employer must either allow the employee to serve the required notice period or provide salary in lieu of notice, based on the applicable contractual notice period specified in the employment agreement.
  • Retrenchment benefit: Employees who have served the company for at least 2 years are eligible for retrenchment benefit. Those with less than 2 years’ service could be granted an ex-gratia payment out of goodwill. The amount generally depends on the employment contract or collective agreement. MOM’s prevailing norm is between two weeks and one month’s salary for each year of service, depending on factors such as industry practice and the company’s financial position.
  • Deductions: Only lawful deductions should be made, with each deduction properly supported and clearly itemised on the final payslip.

Statutory Submissions That Must Not Slip

Retrenchment does not put the normal compliance calendar on hold. Some obligations continue as usual, while others become particularly important when an employee leaves the organisation.

Three areas require close attention:

  • Central Provident Fund (CPF): CPF contributions remain payable on salary and other components of final pay that qualify as wages. However, retrenchment or termination benefits themselves are generally not subject to CPF contributions.
  • Tax clearance for non-Singapore citizens: Where tax clearance is required, employers must file Form IR21 with the Inland Revenue Authority of Singapore (IRAS) at least one month before the employee ceases employment. Moreover, employers should withhold monies due to the employee from the point the employer becomes aware of the impending cessation. This generally applies to employees who are not Singapore Citizens, including Singapore Permanent Residents, subject to applicable exemptions.
  • Employment records: Employers must retain the required employment and salary records for the statutory period. For ex-employees, records must generally be kept for one year after the employee leaves, covering the latest two years of employment records. For tax and payroll purposes, records need to be kept for 5 years.

Payroll Documentation and Audit Trail

Accurate payroll records help employers explain final payment calculations, address employee queries, and resolve discrepancies that may arise after retrenchment. Maintaining a clear audit trail also makes it easier to trace adjustments and verify that payments were properly processed.

Employers should keep the following records for each affected employee:

  • Supporting payroll records: Salary details, leave balances, contractual entitlements, and supporting documents for applicable benefits and deductions.
  • Calculation and approval records: A breakdown of final pay calculations, including any adjustments made and the corresponding review and approval records.
  • Payslips and payment confirmations: Itemised final payslips, payroll reports, and proof of payment to verify the amounts disbursed.


These records support the broader retrenchment process, which involves several compliance requirements and deadlines, as outlined below.

Why Companies Outsource Payroll During Restructuring

Restructuring places unusual pressure on payroll teams precisely when accuracy matters most. This is often when organisations reconsider whether the exercise should be managed entirely in-house or with specialist support:

  • Capacity when pressure is highest: Internal teams may already be occupied with the wider restructuring exercise, while payroll accuracy still needs to be maintained.
  • Specialist calculations: Notice pay, leave encashment, final-pay calculations, and IR21 processing can become more difficult when deadlines are tight, particularly for teams with limited experience handling retrenchments.
  • Continuity: An external provider can keep payroll processing and compliance activities on track while the wider organisation is undergoing change, reducing the risk of missed deadlines or incomplete filings.

How BoardRoom Supports Employers Through Retrenchment

BoardRoom’s payroll services support employers through the retrenchment payroll cycle:

  • Final pay processing: Calculation and disbursement of final pay, including salary, notice pay, leave and applicable benefits, with reconciliation before release.
  • Statutory handling: Support with CPF submissions and IR21 tax clearance requirements, where applicable.
  • Controls: Maker-checker review of final settlements before release, helping reduce the risk of errors reaching departing employees.

Getting Retrenchment Right From the Start

Retrenchment is both a payroll and compliance exercise, and it is conducted under scrutiny from employees, regulators, and other stakeholders. Preparation protects both the employer and the departing employee.

Getting notice, final pay, documentation, and statutory submissions right the first time is essential. A well-controlled process reduces the risk of disputes, missed deadlines, and payment errors at a time when the organisation is already under pressure.

BoardRoom supports Singaporean organisations by managing retrenchment payroll, handling statutory filings, and providing expert tax advisory and filing services for foreign nationals needing IR21 clearance.

Contact BoardRoom to discuss how specialist payroll and compliance support can help manage your restructuring exercise.

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

Business Article

Singapore AGM Season 2026: Insights and Trends From 167 General Meetings

SHARE:
16 Oct 2026
Singapore AGM Season 2026: Insights and Trends From 167 General Meetings
167general meetings serviced in April 2026
44.53%of SGX-listed companies managed by Boardroom
+21%attendance of shareholders vs 2025
55%of physical meetings used e-polling
−26%proxy forms received, to 5,761

As the number one share registrar in Singapore and Malaysia by market capitalisation, and Singapore’s leading share registry services provider, BoardRoom serviced 167 annual general meetings (AGMs), extraordinary general meetings (EGMs), and special general meetings in April 2026. These represented 44.53% of companies listed on the Singapore Exchange (SGX).

April remains the peak of Singapore’s AGM calendar because most SGX-listed issuers close their financial year on 31 December and must hold the AGM within four months of the year end, under SGX Listing Rule 707(1) and section 175 of the Companies Act 1967.

About the data: This report covers the 167 general meetings BoardRoom serviced in April 2026. Year-on-year comparisons are based on companies that held April meetings in both 2025 and 2026.

Key takeaways

  • 64%of the 167 meetings were held in the final week of April, and 97% were held in physical mode.
  • +375%rise in hybrid attendance. Total attendance rose 21% to 19,709 among companies that met in both years.
  • 55%of physical meetings used electronic polling, and 94% of those used handsets.
  • 5,761proxy forms received, down 26%. The most common meeting now runs one to one and a half hours.

Singapore: The April 2026 Season

Meeting format: when and how companies met

Nearly two thirds of meetings were held in the final week of April. 29 April alone accounted for 21% of the total.

Meetings by week, April 2026 (n = 167)

Week beginning 13 April
13 (8%)
Week beginning 20 April
47 (28%)
Week beginning 27 April
107 (64%)

Of the meetings held on 29 April, 37% started at 10am, compared with 35% on the same date in 2025.

Physical meetings remained the norm: 97% were held in physical mode and 3% were hybrid, up from 1% in the 2025 season.

Meeting format by season

2025 season (174)1% hybrid
2026 season (167)3% hybrid
PhysicalHybrid

Communication: Hardcopy Notices Remain Universal

Every meeting mailed a hardcopy notice of meeting, proxy form, or letter to shareholders and unitholders.

Communication practice (n = 167 meetings)

Hardcopy notice, proxy form, or letter mailed
167 (100%)
Hardcopy annual report or circular available on request
138 (82%)
Hardcopy annual report or circular mailed
26 (16%)
Switched from on request in 2025 to no on-request option in 2026
3 (2%)

The 16% mailing rate is broadly in line with the 14% recorded in 2025. Making hardcopy annual reports or circulars available on request remained the most common approach, used at 82% of meetings compared with 86% in 2025.

Attendance: Up 21% Year on Year

Among the 147 companies that held April meetings in both years and reported attendance for both, total attendance rose 21% to 19,709.

Physical attendance increased by 18%, while hybrid attendance rose 375% from a low base.

Physical18,901+2,817 (+18%)
Hybrid808+638 (+375%)
Total19,709+3,455 (+21%)
Attendance, 147 companies with meetings in both years
Season Physical Hybrid Total
2025 16,084 170 16,254
2026 18,901 808 19,709
Change +2,817 (+18%) +638 (+375%) +3,455 (+21%)

Shareholder Engagement: Questions Before the Meeting

Nearly every meeting (99%) gave shareholders a way to submit questions in advance. Many companies used BoardRoom’s Question Deposition Service to receive those questions, through the channels below.

Question Deposition Service channel (Total of 83 companies)

Designated email address and post
48
Post
30
Designated email address
4
Designated email address, post and pre-registration site
1

Questions were received before 57% of meetings, up from 51% in 2025. Of these, 93% answered the questions through SGXNET ahead of the meeting. This excludes meetings that received questions only from the Securities Investors Association (Singapore).

The five topics shareholders raised most often were:

  1. Company strategy and future plans
  2. Financial performance
  3. Dividends and distributions
  4. Mergers, demergers, acquisitions and divestments
  5. Share or unit buy-backs and renewal of the share purchase mandate

Strategy questions this season were frequently framed around Middle East tensions and the resulting rise in global fuel prices, and their effect on material, freight, logistics and insurance costs, supply-chain lead times and margins. Company strategy moved to first place from second in 2025, when questions on United States tariffs drove the topic.

Voting and Proxy Processing

Electronic polling was used at 55% of physical meetings, and 94% of those used handsets rather than shareholders’ own devices.

Where paper polling was used, counting could take up to half of the meeting time.

Poll type by meeting format
Meeting format Poll type Meetings Share of format
Physical (162) Paper poll, Excel (manual) 34 21%
Paper poll, BR Poll (semi-automated) 39 24%
Electronic poll, handsets 84 52%
Electronic poll, bring your own device (BYOD) 5 3%
Hybrid (5) BYOD on site and online voting for remote attendees 3
Handsets on site and online voting for remote attendees 2

Electronic polling was used at 52% of physical meetings in 2025. This points to a continued, gradual shift towards e-polling.

Proxy deposition

A total of 118 companies used BoardRoom’s Proxy Deposition Service, the same number as in 2025. Most accepted proxies through both email and post.

Proxy Deposition Service channel (Total of 118 companies)

Email address and post
96
Post
18
Email address, post and pre-registration site
3
Email address
1
Proxy forms, 2025 vs 2026
Proxy forms 2025 2026 Change
Received 7,780 5,761 −2,019 (−26%)
Processed 6,798 4,916 −1,882 (−28%)

The five resolutions that attracted the most poll votes were unchanged from 2025:

  1. Re-election of directors
  2. Financial report
  3. Auditor
  4. Dividend
  5. Directors’ fees

Meeting Duration

Meetings ran longer than in 2025. The largest duration category was one hour to under one and a half hours, covering 36% of meetings.

Overall, 62% of physical meetings lasted between 30 minutes and one and a half hours.

Duration of all 167 meetings

Under 30 minutes
9 (5%)
30 minutes to under 1 hour
43 (26%)
1 hour to under 1.5 hours
60 (36%)
1.5 hours to under 2 hours
33 (20%)
2 hours to under 2.5 hours
20 (12%)
2.5 hours and above
2 (1%)
Duration by meeting format
Duration Physical Hybrid Total Share
Under 30 minutes 9 0 9 5%
30 minutes to under 1 hour 42 1 43 26%
1 hour to under 1.5 hours 59 1 60 36%
1.5 hours to under 2 hours 32 1 33 20%
2 hours to under 2.5 hours 19 1 20 12%
2.5 hours and above 1 1 2 1%
Total 162 5 167 100%

Among the 157 companies that held meetings in both years, meetings lasting between one and two hours rose from 43% to 57% of the total, while meetings lasting less than an hour fell from 41% to 31%.

Duration, 157 companies with meetings in both years
Duration 2025 season 2026 season Change
Under 30 minutes 11 8 −3
30 minutes to under 1 hour 54 40 −14
1 hour to under 1.5 hours 37 58 +21
1.5 hours to under 2 hours 30 31 +1
2 hours to under 2.5 hours 21 18 −3
2.5 hours and above 4 2 −2

Refreshments and Door Gifts

Refreshments remained the most common provision. In 2026, 57% of meetings provided refreshments only, while 34% provided neither.

Among the 156 companies with meetings in both years, the 2025 figures were 68% for refreshments only, 2% for vouchers or door gifts only, and 30% for neither.

Provision at 167 meetings

Refreshments only (95)Voucher or door gift only (15)Nothing provided (57)

Among the 156 companies with April meetings in both years, fewer provided refreshments only, while vouchers and door gifts increased from a low base.

Overall, 6% fewer provided refreshments, vouchers or door gifts than in 2025.

Provision, 156 companies with meetings in both years
Provision 2025 2026 Change 2025 to 2026
Refreshments only 106 89 −16%
Voucher or door gift only 3 13 +333%
Nothing provided 47 54 +15%

Key Considerations for the Next Season

  • Book early for the final week of April64% of meetings were held during that week, with 21% on 29 April alone.
  • Plan for more attendees and longer meetingsAttendance rose 21%, while the typical meeting runs one to one and a half hours.
  • Treat hybrid as a live optionOnly 3% of meetings offered the option, but hybrid attendance rose 375%.
  • Consider electronic pollingPaper polls took up to half of the meeting time, while electronic polling was already used at 55% of physical meetings.
  • Use the pre-meeting question window57% of meetings received questions in advance, giving companies an opportunity to address shareholder concerns before the live session.

BoardRoom’s share registry, AGM management, e-polling and proxy processing teams supported BoardRoom manages 44.53% of SGX-listed companies through the 2026 season, and the same teams carry issuers through dividend distribution after the meeting, the basis on which BoardRoom remains Singapore’s leading share registry services provider.

BoardRoom’s Malaysia AGM season report covers January to June 2026.

About BoardRoom

One BoardRoom. One Partner. Complete Corporate Services Delivered Seamlessly.

From start-up to scale, BoardRoom supports growth with integrated compliance expertise, bringing corporate secretarial, tax, payroll, accounting, fund solutions, share registry, employee share plans and sustainability services together through a single trusted partner.

To discuss support for your next general meeting in Singapore, contact BoardRoom.

Frequently Asked Questions

1. When must an SGX-listed company hold its AGM?

Within four months of its financial year end, under SGX Listing Rule 707(1) and section 175 of the Companies Act 1967.

2. How does e-polling work at a Singapore AGM?

Shareholders and proxies register on arrival and receive a handset, or use their own device, to cast votes on each resolution. Votes are tallied electronically and the scrutineer certifies the result, which removes manual counting.

What XBRL Filing Means for Singapore Companies and When Outsourcing Makes Sense

What XBRL Filing Means for Singapore Companies and When Outsourcing Makes Sense

For companies, eXtensible Business Reporting Language (XBRL) filing means converting financial statements from a document designed for people into structured financial data that the Accounting and Corporate Regulatory Authority’s (ACRA) systems can read, validate and compare. XBRL uses digital tags to identify financial information, such as revenue, assets, and net profit, so that the data can be processed consistently by software.

This is more than a file-format conversion. The company must determine which filing requirement and XBRL template apply, map each relevant financial-statement item to the ACRA Taxonomy, complete the required fields, resolve validation issues, and ensure that the XBRL data agrees with the financial statements presented at the annual general meeting or circulated to members.

The practical question is therefore not only whether the company can use the free BizFinx Preparation Tool, but whether the finance team has the capacity, accounting judgement, and current taxonomy knowledge to prepare an accurate filing within the annual-return timetable. This article explains what XBRL filing involves, the common challenges, and why outsourcing makes sense.

What XBRL Filing Means for Companies

ACRA states that Singapore-incorporated companies must prepare financial statements, except for dormant relevant companies, and must file financial statements with ACRA unless exempted. The filing format and extent depend on the company’s nature and size. Companies should therefore first confirm whether filing is required and which XBRL template applies.

The main filing categories are:

Full XBRL 
  • Applies to companies that are not classified as small and non-publicly accountable. 
  • The template contains about 210 data elements. 
Simplified XBRL 
  • Applies to smaller and non-publicly accountable companies, where both revenue and total assets do not exceed S$500,000 for the current financial year. 
  • The template contains about 120 data elements. 
XBRL FSH 
  • Applies to banks, finance, and insurance companies regulated by the Monetary Authority of Singapore (MAS). 
  • The template contains about 80 data elements. 

Companies such as dormant relevant companies and solvent exempt private companies may be exempt from filing financial statements, while companies limited by guarantee, foreign companies, and companies using other accounting standards approved by ACRA have separate filing requirements.

Companies generally map and validate the financial statements in the BiZFinx Preparation Tool, upload the XBRL file, and then file the annual return in BizFile+. ACRA notes that if the annual return is not lodged after the XBRL upload, the uploaded date may lapse and require re-uploading.

Why XBRL Filing Can Be Challenging

The most demanding part is often mapping. ACRA describes its taxonomy as a dictionary for XBRL language. Preparers must match line items in the financial statements to the relevant taxonomy concepts, using one-to-one, many-to-one, one-to-many, or best-fit mapping where appropriate. This requires accounting judgement because the wording in the financial statements may not exactly match the taxonomy.

These errors can lead to amendments. If an amendment is missed and the filing remains incorrect after the deadline, penalties may follow. An accountant who has prepared hundreds of filings is more likely to recognise how unusual line items should be tagged, while a preparer completing one filing a year may be learning the process under deadline pressure.

Other challenges include keeping the XBRL file aligned with late changes to the final financial statements, checking comparative figures imported from an earlier filing, completing every applicable template, and resolving validation errors. ACRA notes that not all data elements may be imported when taxonomy versions change, so preparers must check the accuracy and completeness of comparative figures rather than rely on a simple roll-forward.

The Business Impact of Getting It Wrong

  • Penalties: An annual return filed up to three months late carries a S$300 penalty, and S$600 beyond that, applied automatically in BizFile+. Repeated breaches can bring composition sums of at least S$500, court fines of up to S$10,000 per charge, and disqualification for a director with three filing offences in five years.
  • Record: Late or corrected filings stay on the company’s ACRA record. Banks and buyers check that record before they lend or invest, and a history of late filings costs the company their confidence.
  • Internal cost: Every amendment sends the accountant back to re-map, re-validate and re-upload the file while the deadline keeps running. At year-end, that means overtime or a hire to cover the gap and drive up the cost.

Directors are responsible under Section 201 of the Companies Act 1967 for laying financial statements before the company at its AGM, and those financial statements must comply with the Accounting Standards and give a true and fair view of the company’s financial position and performance.

Why Outsourcing Can Make Sense

Factor  In-house works when  Outsource when 
Disclosure complexity  Single entity with simple accounts, same disclosures as last year.  Complex or group accounts, restructuring, a new accounting policy, or a first-time filing. 
Team capacity  Team is available during the filing window.   No internal capacity is available due to existing finance and audit commitments.  
Mapping skill  An accountant on the team has prior mapping experience in the Preparation Tool.   No team member has mapping experience, or the individual with experience has left the team. 
Cost Considerations   Internal capacity is available at no incremental cost.   Internal delivery would require overtime, reassignment of existing tasks, or additional headcount.  

Outsourcing is particularly sensible when the filing is complex, the team prepares XBRL only occasionally, deadlines overlap with audit and year-end work, or internal reviewers are not familiar with the latest ACRA taxonomy and validation requirements. A specialised provider can bring together mapping, validation, review and filing support, while the company’s finance team focuses on confirming that the output agrees with the approved financial statements.

Why Finance Teams Outsource to BoardRoom

  • Tagging that ACRA accepts: BoardRoom’s accountants have supported more than 1,000 companies through XBRL conversion, so an unusual line item is rarely unusual to them.
  • Validation and amendments are our work: The validation run, review of possible errors, and any amendment round sit with BoardRoom, not with your team.
  • Your role becomes review and sign-off: You check the output against the signed statements rather than build it.
  • The filing and annual return move together: When BoardRoom also acts as your corporate secretary, the XBRL file and the annual return are lodged as one job.

A Practical Decision for Finance Teams

In-house preparation can work well for a straightforward, recurring filing where an experienced preparer has sufficient time, and the company maintains strong review controls. Outsourcing becomes more compelling when the filing is new, complex or time-sensitive, or when internal capability is limited. The objective is not simply to transfer an administrative task. It is to reduce execution risk, improve consistency and free the finance team to concentrate on review, approval and core reporting responsibilities.

BoardRoom supports Singapore companies with XBRL preparation, mapping, validation and filing coordination. If your team is assessing whether to retain the work in-house or outsource it, consider the complexity of the financial statements, the experience of the preparer, available review capacity and the consequences of rework close to the filing deadline. Contact BoardRoom to discuss the scope of your next filing.

Navigating Business Restructuring in Singapore: A Strategic Guide for Corporate Planning

Navigating Business Restructuring in Singapore: A Strategic Guide for Corporate Planning

As business conditions evolve, corporate boards and executive leadership teams across Singapore periodically review their business structures as part of their broader strategic and financial planning. These reviews provide an opportunity to reassess operational performance, capital structures, and group structures.

These reviews may reveal that an existing corporate structure no longer supports future growth, risk mitigation, or value preservation. For companies considering restructuring, Singapore offers several statutory pathways under the Companies Act 1967, the Insolvency, Restructuring and Dissolution Act 2018 (IRDA), and prevailing tax legislation.

The appropriate route depends on the company’s financial position, commercial objectives, stakeholder interests, and tax implications.

Operational Restructuring Without Insolvency

Solvent restructuring can help otherwise healthy groups simplify governance, unlock value, or prepare business units for expansion or divestment.

Internal Reorganisation

An internal reorganisation involves transferring assets, intellectual property, or business units between related entities. Common objectives include isolating higher-risk business activities, aligning operations with regional management structures, and simplifying the group for a more tax-efficient operating model.

Section 210 Scheme of Arrangement

Under the Companies Act 1967, Section 210 enables a solvent company to propose a court-sanctioned compromise or arrangement with its members or creditors. It can support complex exercises such as:

  • Corporate amalgamations: Merging entities within a group to eliminate redundant administrative layers.
  • Share swaps and restructurings: Reorganising equity holdings to facilitate new investments or joint ventures.
  • Takeovers and privatisations: Implementing structured buyouts requiring judicial oversight to bind all stakeholders.

Capital Reduction

Governed by Section 78 of the Companies Act 1967, capital reduction allows a company to reduce its paid-up share capital. This can be used to return surplus capital to shareholders, write off accumulated losses to clean up the balance sheet, or simplify the capital structure ahead of a funding round or strategic exit.

Tax Considerations

Restructuring transactions are rarely tax-neutral. Transfer of assets or shares between related entities can trigger stamp duty liabilities, Goods and Services Tax (GST) exposures, or corporate income tax implications. Early tax planning is essential to identify available statutory reliefs and prevent unintended tax leakages.

Restructuring Under Financial Stress: The IRDA Framework

When financial pressures threaten a company’s viability, the focus shifts from operational efficiency to business rescue and asset preservation. The IRDA provides distressed companies with several mechanisms designed to facilitate restructuring and give viable businesses an opportunity to recover.

Scheme of Arrangement

An IRDA scheme can provide distressed companies with important protections, including:

  • Automatic moratoria: Grants immediate, temporary breathing room by restraining creditors from initiating legal or enforcement actions while the company formulates its proposal.
  • Super-priority rescue financing: Allowing new financing to receive priority status or security over existing creditors.
  • Cross-class cram-down: Allowing courts, where appropriate, to sanction arrangements despite objections from certain creditor classes.

Judicial Management

Judicial management provides an alternative for companies facing severe financial distress, particularly where creditor confidence in existing management has deteriorated. A court-appointed judicial manager assumes control to rescue the business as a going concern or achieve a better outcome through asset realisation than a straight liquidation.

Simplified Insolvency Programme

For eligible micro and small enterprises, the Simplified Insolvency Programme offers a faster, lower-cost route to restructuring debts or winding up operations, subject to prescribed asset and liability criteria.

Voluntary Winding-Up Routes for Solvent and Insolvent Companies

Restructuring can also involve an orderly exit. The appropriate winding-up route depends on the company’s financial health.

Members' Voluntary Liquidation (MVL)

An MVL is designed for solvent entities that have ceased trading, fulfilled their purpose, or are being dissolved for group rationalisation. As a formal process for closing a solvent company, an MVL requires directors to meet specific statutory obligations, including providing a statutory Declaration of Solvency confirming that the company can pay its debts in full within 12 months from the commencement of the winding up.

Creditors' Voluntary Liquidation (CVL)

A CVL applies where a company is insolvent and unable to meet its debts as they fall due. Directors can proactively initiate the process, with a private liquidator appointed to realise assets and distribute proceeds to creditors according to statutory priorities.

Striking Off

For dormant companies that meet the Accounting and Corporate Regulatory Authority’s (ACRA) requirements, striking off can provide a simpler and more economical alternative to formal liquidation. The company must generally have ceased trading, have no outstanding assets or liabilities, and have no ongoing regulatory matters.

Tax Clearance

Before a winding-up is completed, tax matters must be addressed with the Inland Revenue Authority of Singapore (IRAS). This includes reviewing historical filings, unutilised losses and capital allowances, capital reductions, and the treatment of remaining corporate assets. Tax clearance is required before final distributions can be made to shareholders by the liquidator.

Tax and Governance Issues that Drive Route Selection

Selecting a restructuring pathway requires boards to consider more than the immediate commercial objective:

  • Stamp duty: Transfer of shares or immovable property may attract stamp duty. Boards should assess whether statutory relief under Section 15 of the Stamp Duties Act is available.
  • GST implications: Asset transfers create GST liabilities. A properly structured transfer of a going concern (TOGC) may qualify for GST relief, subject to the relevant requirements.
  • Capital and dividend treatment: Though Singapore generally does not tax capital gains, boards must distinguish between a return of capital and a distribution of accumulated profits to prevent unexpected tax exposures for recipients.
  • Employees: Restructuring may require changes to employment arrangements, Employee Share Option Plans (ESOPs), and redundancy processes, with compliance under the Employment Act 1968.
  • Director duties: As a company approaches insolvency, directors must increasingly consider creditor interests. Delaying action or pursuing an inappropriate restructuring route can increase exposure to personal liability for wrongful trading or breaches of statutory duties.

How Boards Evaluate the Right Route

Boards should assess potential restructuring options systematically with their professional advisers:

Assess Solvency

Use the cash flow test to determine whether the company can pay its debts as they fall due, alongside the balance sheet test to assess whether its total liabilities exceed its total assets. These assessments can help determine whether solvent restructuring or an IRDA process is appropriate.

Map Stakeholders

Map out your corporate ecosystem. Balance the competing interests of secured/unsecured creditors, shareholders, employees, customers, and regulators.

Define the commercial objective

Determine whether the priority is business rescue, asset disposal, group simplification, or an orderly wind-up.

Assess Time and Cost

Compare the resources and timelines required for court-supervised processes against simpler administrative routes.

Align Advisers

Coordinate corporate counsel, restructuring, tax, and corporate secretarial advisers to minimise execution delays and unnecessary costs.

Strategic Relevance by Corporate Role

These considerations are particularly relevant to:

  • Boards and chief financial officers (CFOs) reviewing group architecture, capital structures, or operational viability as part of ongoing financial and strategic planning.
  • Private equity (PE) sponsors and shareholders considering exits, recapitalisations, or divestments.
  • Distressed-company directors evaluating rescue, judicial management, or winding-up options.
  • Founders and family shareholders seeking to simplify corporate structures or close dormant entities.

Taking the Next Step in Your Restructuring Journey

Business restructuring requires careful decisions around solvency, stakeholder interests, tax exposure, and execution timing. Selecting the appropriate statutory route can help preserve enterprise value, minimise financial leakage, and manage directors’ regulatory obligations.

As you weigh your options, an experienced corporate services partner can help navigate the process. BoardRoom supports companies in Singapore with corporate restructuring services, including MVL, capital reductions, and corporate secretarial compliance.

Contact our team today to discuss how we can help you structure your business for its next phase of growth.